
Freelancer mortgages are not some rare unicorn product reserved for a lucky few who somehow cracked a secret code.
But if you have ever watched a loan officer’s face shift the moment you said “self-employed,” you already know the system was not exactly built with people like us in mind.
This guide is written for self-employed borrowers in the United States. It explains, in plain language, what documents lenders commonly ask for, how different U.S. loan types treat self-employment income, and what questions to ask before you apply.
The traditional mortgage system still treats variable income as a red flag. Closing that gap is often about information and knowing where to look.
This guide fixes that.
Whether you are a freelance writer, a graphic designer, an IT contractor, a gig economy worker, or a small business owner running your own show, this article walks you through exactly how freelancer mortgages work in 2026, which lenders are genuinely good for your situation, what documents you need, and the mistakes that kill applications before they even get started.
Let us get into it properly.Which Mortgage Type Is Best for Freelancers
The Legal Documents Freelancers Need for a Mortgage Application And What They Actually Mean
Here is where the mortgage process gets real for most freelancers and where most applications fall apart before they ever reach an underwriter.
A salaried employee walks into a lender’s office with recent pay stubs and a W-2. The lender has a simple, standardized way to verify that income. As a freelancer, you are going to walk in with a folder. A large folder. And every document in that folder has a specific purpose that the lender’s underwriting team will evaluate carefully.
Understanding what each document represents legally not just what it is gives you a serious advantage. It means you know exactly what you are submitting, why it matters, and what to do if something is missing or unclear.
Here is what you will typically need, and the legal weight each document carries.
- Two to Three Years of Filed Federal Tax Returns (Form 1040 and Schedules)
For self-employed borrowers, that means your filed Form 1040 with Schedule C attached. Schedule C is your official profit and loss statement as a self-employed individual. It is what the IRS has on record as your net business income after deductions.
This is where your self-employment tax filing history becomes directly relevant to your mortgage application not just to the IRS, but to any lender evaluating your financial stability.
2. Proof of Consistent Contracts or Client Agreements
This one surprises people. Many lenders particularly those offering specialist self-employed mortgage products will ask to see evidence of ongoing client relationships. A current contract with a client that shows a retainer arrangement, a long-term service agreement, or a signed statement of work covering the next six to twelve months can materially strengthen your application.
This is not just financial evidence. It is legal documentation that your income has continuity that you are not a one-project contractor whose income may stop the moment a single client ends a relationship.
If you do not currently use written contracts with your clients, this is one of the most financially costly consequences of that habit. A verbal agreement cannot be presented to a mortgage underwriter. A signed freelance contract can. Getting your client relationships formalized in writing is not just a legal protection it is a financial asset.
3. Business Bank Statements (12 to 24 Months)
Lenders want to see that your freelance income is deposited into a dedicated business account regularly and consistently. Irregular deposits or the mixing of personal and business income in a single account raise red flags during underwriting.
From a legal standpoint, a dedicated business account also demonstrates that you operate your freelance work as a genuine business not a side activity. This distinction matters, particularly if you operate as a sole proprietor, LLC, or S-Corporation, because lenders treat these structures differently when calculating eligible income.
4. An Accountant’s Certificate or Reference Letter
Many lenders assessing self-employed applications will ask for a reference letter from a qualified accountant confirming your income over two to three years. This letter carries weight because it comes from a licensed professional who is staking their professional standing on the accuracy of the figures they confirm.
If you do not currently use an accountant, this is worth reconsidering before applying for a mortgage. A certified accountant’s letter can unlock mortgage products that are not available to self-employed applicants without one.
5. Proof of ID and Address The Same as Everyone Else
Passport, driver’s license, utility bills. No surprises here. This is standard identity verification that applies to every mortgage applicant regardless of employment status.
One important note on tax deductions and mortgage applications
This is the part that catches many freelancers completely off guard.
If you have been maximizing your self-employment tax deductions, which is smart tax planning, your net income on Schedule C may look significantly lower than what you actually deposited into your account each month. Lenders typically calculate eligible income based on net profit after deductions, not gross revenue, in the lender’s eyes.
That is why this dynamic matters before you apply: a lower net income on your return can mean a lower qualifying income, even if your cash flow is higher. Ask a lender how it will treat your returns before you assume a qualifying figure.
Understanding this dynamic before you apply means you can choose between lenders that use gross revenue (some specialist lenders do) and those that use net profit, and position your application accordingly.
The legal paper trail of your freelance business your contracts, your tax returns, your invoices, your business accounts is not just compliance documentation. It is the foundation of your financial credibility. Build it carefully, maintain it consistently, and it will open doors that most lenders make look impossible for freelancers.
Can a Freelancer Get a Mortgage? Here Is the Real Answer for 2026
Yes, in many cases. Freelancers can qualify, but approval depends on the loan type, the lender, and how your income is documented.
Freelancer mortgages exist across every major loan category, including conventional loans, FHA loans, VA loans, and a rapidly growing category called Non-QM loans that were practically invented for people in your exact situation.
The confusion comes from one fundamental problem. Lenders built their systems around W-2 employees. When a loan officer receives a payslip, they multiply it by 12 and arrive at a clean annual income figure. Simple. Neat. Easy to enter into an underwriting system.
Your income does not work like that.
Maybe you earned $65,000 one year and $92,000 the next. Maybe you had a strong quarter followed by a quieter one while you were between big projects. Maybe you write off every legitimate business expense available to you, which brings your taxable income down significantly even though your actual cash flow is healthy and consistent.
None of that makes you a risky borrower. It just means you need a lender who knows how to read your full financial picture rather than just the simplified version that fits on a payslip.
A sustainable freelancing income built over multiple years can demonstrate financial discipline. That is the kind of resilience lenders look for, but it does not by itself guarantee approval. Lenders still underwrite income, credit, debts, and the property.
The challenge is not your creditworthiness. The challenge is knowing which lenders and which loan types actually understand that.
What Makes Freelancer Mortgages Different From Regular Mortgages
A freelancer mortgage is not a separate, specially named loan product sitting in a lender’s catalog between “conventional” and “jumbo.”
A freelancer mortgage is simply a standard residential mortgage applied for by someone who earns income through self-employment rather than a salaried position. The mortgage itself works exactly the same way. What changes is how the lender verifies and calculates your income before deciding whether to approve you.
Here is what shifts when you are self-employed:
Income verification changes completely. Instead of pay stubs, lenders want tax returns, bank statements, 1099 forms, and sometimes CPA-prepared profit and loss statements.
Income calculation gets more nuanced. Lenders look at your net income after business expenses rather than gross revenue, or in the case of bank statement loans, your average monthly deposits across 12 to 24 months.
Income stability becomes a central concern. Lenders want to see a pattern of consistent or growing income. Two years of history carries far more weight than one exceptional year with a question mark after it.
Business longevity matters. Most lenders want to see at least two years of self-employment history. Some will work with one year under specific conditions. Very few will go below that threshold without strong compensating factors.
Understanding these differences before you walk into any lender conversation saves you enormous time and prevents the kind of frustration that sends freelancers into a spiral of Googling at midnight.
Mortgage for Self Employed Borrowers: Your Full Menu of Loan Options in 2026
This is where a lot of articles fall genuinely short. They talk about one or two loan types and leave you thinking those are your only options. In 2026, the landscape has expanded considerably. You have more paths available than most people realize.
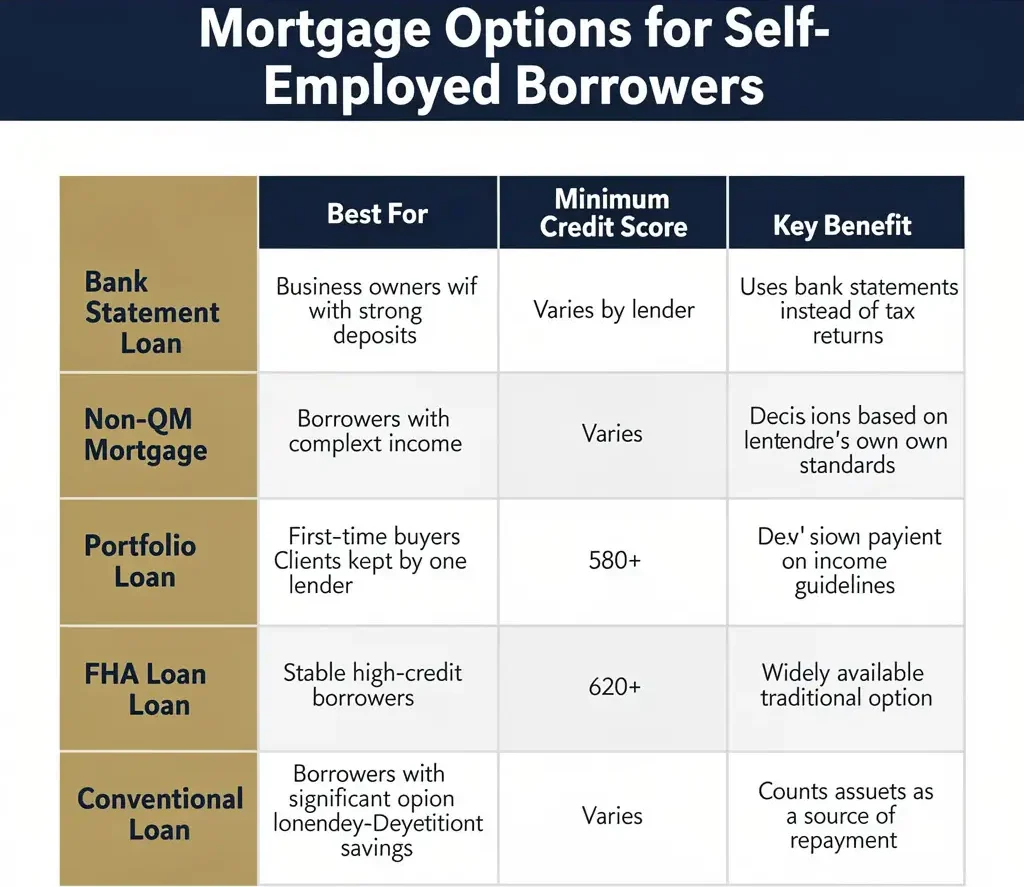
Conventional Loans for Self-Employed Borrowers
Conventional loans remain the most common route for freelancers who have a solid two-year tax history and whose net income after legitimate deductions still paints a strong enough picture for a lender.
Fannie Mae and Freddie Mac, the two government-sponsored entities that back the majority of conventional loans in the US, have specific guidelines for self-employed income verification. Under Fannie Mae’s Selling Guide (B3-3.1-09), the lender must analyze cash flow and income trends, documented on Form 1084, rather than simply averaging the last two years of federal tax returns, including all schedules. Business tax returns may not be required when the borrower has been self-employed for at least five years, owns 25% or less of the business, and shows rising income, and a one-year route is possible in limited circumstances. For borrowers with less than two years of self-employment history, the lender generally looks for at least 12 months of income on the latest signed returns plus prior income in the same field at the same or a greater level. Confirm how your lender applies these rules before you apply.
If your net income has been consistent or growing over that period, a conventional loan is often your cleanest and most affordable path. If your most recent year was significantly lower than the previous one, the lender must analyze the trend and the reasons for the decline, and a declining trend can reduce your qualifying income. Ask the lender how it will treat a decline before you apply.
What you typically need for a conventional freelancer mortgage:
Two years of personal tax returns with all schedules attached. Business returns if you operate as an LLC or S-Corporation, subject to the exceptions described below. Credit history, down payment, and debt-to-income requirements vary by lender and program, so confirm the current requirements for the program you are considering before you apply.
The debt-to-income ratio matters enormously here. Your total monthly debt payments, including the new mortgage, are compared with your gross monthly qualifying income, and the maximum ratio a lender will accept varies by lender and program. Ask a lender for its current limit before you assume a figure.
FHA Loans: A Strong Option for Freelancers With Lower Credit Scores
FHA loans are government-backed mortgages insured by the Federal Housing Administration, designed to help borrowers who might not qualify for conventional financing due to credit history or down payment limitations.
For freelancers, FHA loans offer a few specific practical advantages that matter in 2026.
FHA loans may be available to borrowers with lower credit scores than conventional loans require, but the minimum score and down payment a lender will accept vary, and individual lenders may apply additional requirements (lender overlays) on top of FHA standards. Confirm the current credit and down-payment requirements with an FHA-approved lender, and check HUD Handbook 4000.1 for the current program rules.
The income documentation requirements mirror conventional loans. You still need two years of tax returns and will be assessed primarily on your net self-employment income. However, FHA-approved lenders sometimes take a more human approach to complex income situations than automated conventional underwriting systems do.
The tradeoff is mortgage insurance. FHA loans require mortgage insurance premiums, including an upfront premium and an annual premium. How long the annual premium lasts depends on the loan terms, so confirm the current premium amounts and duration with your lender and in HUD Handbook 4000.1 before you rely on a figure. Factor the full insurance cost into your calculations before committing to this path.
VA Loans for Freelance Veterans and Service Members
If you are an eligible veteran or active-duty service member who has gone the independent route, VA loans remain one of the most powerful mortgage products available to anyone in the US market.
Nearly 90% of VA-backed loans are made without a down payment, according to VA.gov, and VA loans do not carry private mortgage insurance as such. A VA funding fee does apply, and lenders may impose additional standards beyond VA requirements. You will also need a Certificate of Eligibility (COE) showing your VA loan entitlement. Interest rates can be competitive, but compare current offers rather than assuming VA rates will beat conventional rates.
The distinctive element of VA loans is the residual income requirement. After all debt obligations are accounted for, you need to demonstrate sufficient leftover income each month based on your family size and geographic location. The required residual income amount varies by region and household size, so ask your lender for the current figure that applies to you rather than relying on a general number.
Bank Statement Loans: The Real Game Changer for Freelancers Who Write Off a Lot
Here is where things get genuinely interesting for a significant portion of the freelancing community.
Bank statement loans are Non-QM mortgage products that allow lenders to evaluate your qualifying income based on 12 to 24 months of personal or business bank statements instead of tax returns.
This matters enormously because of a tension that most smart freelancers face every year.
If you are running your business properly, you are claiming every legitimate deduction available to you. Home office. Equipment. Software. Professional subscriptions. Health insurance premiums. Travel with a genuine business purpose. These write-offs reduce your taxable income, which is excellent for your annual tax bill.
Consider a hypothetical freelancer whose tax return shows $42,000 in net income after deductions while bank statements show $88,000 in deposits over the same period. This is an illustration only, not a program rule: a bank-statement lender applies its own program rules to deposits, including how it treats business expenses and large or non-recurring items, so the qualifying income it calculates may differ substantially from either figure. Ask the lender for its current calculation method before assuming a qualifying amount.
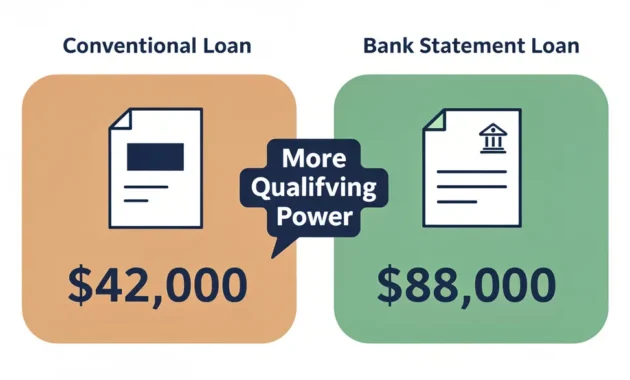
A bank statement loan addresses this problem by looking at verified bank deposits rather than tax-return net income. The lender applies its own program rules to those deposits, including how it treats business expenses and non-recurring deposits, so the qualifying income it calculates varies by program. Ask the lender for its current calculation method and expense treatment before assuming a qualifying amount.
For freelancers whose legitimate write-offs significantly compress their stated net income, bank statement loans can unlock borrowing capacity that conventional products simply cannot reach.
Bank-statement programs vary by lender, so ask each lender for its current program terms, including the statement period it requires, how it treats business expenses and non-recurring deposits, and the rate and down-payment terms that apply to your profile.
Bank-statement loans may carry different rates than comparable conventional products, so compare the rate, fees, and down-payment terms of each offer before deciding whether the additional borrowing capacity is worth the tradeoff.
1099 Loans: Perfect for Independent Contractors and Consistent Gig Workers
A 1099 loan uses your actual 1099 forms, the tax documents your clients send instead of W-2s, as the primary income verification tool.
Rather than relying only on tax-return net income, a 1099 lender may start from your gross 1099 income and apply its own program rules for business expenses. Because those rules vary by lender and program, the qualifying income it calculates may differ substantially from your tax-return net income, so ask the lender for its current calculation method before assuming a figure.
These are Non-QM products with rate structures similar to bank statement loans. But for the right borrower profile, particularly contractors with consistent 1099 income from multiple clients throughout the year, the qualifying income calculation can be transformative.
Asset Depletion Loans: For Freelancers With Strong Savings and Investments
Less commonly discussed but worth understanding, an asset depletion loan allows lenders to count your liquid assets as a form of qualifying income.
The general idea is to divide eligible assets by a number of months to produce a monthly income equivalent. Which assets count, whether any haircut applies, and the divisor used all vary by lender and program, so ask the lender for its current asset-depletion method before assuming a qualifying income figure.
As a hypothetical illustration only, with no asset haircut or eligibility adjustment applied: $480,000 in savings and investment accounts divided by 360 months equals $1,333 per month. This is arithmetic only, not a program rule, and a lender’s actual asset-depletion calculation may differ substantially once its own eligibility rules and haircuts are applied.
This is particularly relevant for freelancers who have accumulated significant savings, whose income is genuinely difficult to document cleanly in a given period, or who recently transitioned to freelancing and do not yet have two full years of history.
Self-Employed Mortgage Requirements: What Lenders Actually Need From You
Let us talk about documentation with real specificity, because this is where the majority of freelance mortgage applications either succeed or fall apart in 2026.
The number one mistake I consistently see is freelancers either assuming their situation is too complicated to bother or assuming the process mirrors what their employed friends went through. Both assumptions lead to problems.
Tax Returns: The Foundation of Conventional Loan Approval
Most lenders want the last two years of complete federal tax returns including every schedule.
For sole proprietors and single-member LLCs taxed as sole proprietors, this means Form 1040 and Schedule C, which shows your business profit and loss in detail.
For partnerships, you need your personal Form 1040 plus the partnership return Form 1065 along with your K-1 showing your distributive share of income.
For S-Corporations, you need your personal Form 1040 plus the S-Corp return Form 1120-S along with your K-1.
One critical practical note: make sure your most recent tax year is filed before you apply. If you are applying mid-year and your prior year return has not been filed yet, this creates complications that can delay or derail your application. Some lenders accept extension confirmations as evidence of a filed return, but many require the actual filed document. Plan your application timing around this reality.
1099 Forms and Income Verification Documents
Gather all 1099 forms for the past two years. The reporting threshold was $600 for payments through 2025 and is $2,000 for payments after December 31, 2025, so check which threshold applied in each year you are documenting. These serve as critical evidence that your income is real, consistent, and coming from legitimate, verifiable sources.
Lenders cross-reference 1099 totals against your tax returns. If your 1099s show $110,000 in gross payments but your tax return shows $48,000 after deductions, a knowledgeable underwriter can see both figures and understand the underlying dynamic. This also strengthens the supporting documentation for bank statement loan applications.
Bank Statements for Self-Employed Mortgage Applications
For conventional loans, lenders typically want two to three months of personal bank statements to verify your down payment source and available cash reserves.
For bank statement loans, the requirement expands significantly to 12 or 24 months of business and personal statements. Make sure these are complete official statements showing your institution’s name, your account number, and your full transaction history, not just downloaded summaries or screen captures.
If your business and personal finances currently run through the same account, some lenders will work with that arrangement. Others strongly prefer clear separation. Going forward, maintaining separate business and personal accounts is worth doing both for mortgage purposes and for your overall financial hygiene as a freelancer.
CPA-Prepared Financial Statements for Mortgage Applications
For LLC owners, partnership members, and S-Corporation owners, lenders typically require CPA-prepared financial statements or business tax returns prepared and signed by a licensed CPA or accountant, usually for the last two years.
Some specialist lenders will accept accountant-prepared accounts even before they have been formally filed with the relevant government authority, but they will typically request a supporting reference letter from your accountant confirming the accuracy of the figures.
An accountant letter for mortgage purposes is a brief professional statement from your CPA confirming your self-employment status, the nature of your business, the length of your trading history, and in some cases their professional assessment of the sustainability of your income. Some lenders specifically request this as supplementary documentation.
Proof of Contracts and Ongoing Business Activity
This is not always required, but for contractors in particular, providing an active contract or recently completed contract is genuinely powerful supporting documentation.
It demonstrates to an underwriter that you are not between engagements but actively working in your field. A contract with three months remaining is evidence of near-term income stability. Multiple completed contracts over recent years demonstrate consistent demand for your skills.
Business bank account statements showing regular client payments arriving over an extended period serve a similar function for project-based freelancers who do not always operate under formal written contracts.
Freelancer Mortgage Lenders: Who Actually Gets Your Situation in 2026
Finding the right lender is not simply about finding whoever has the lowest advertised rate this week. It is about identifying the lender whose income assessment methodology actually works for your specific income structure and documentation profile.
Here is a breakdown of the lender landscape as it stands in 2026.
Specialist and Non-QM Lenders for Self-Employed Borrowers
Non-QM lenders offer bank statement, 1099, and asset depletion products that use documentation other than standard tax returns. Because program terms vary by lender, ask each lender for its current program terms, including the documentation it requires, how it calculates qualifying income, and the rate and down payment terms that apply to your profile.
Mortgage Brokers for Self-Employed Borrowers
Sometimes the most effective path is not approaching lenders directly but working with a mortgage broker who specializes in self-employed applicants and can shop your application across many lenders.
A broker who works regularly with self-employed borrowers understands which lenders are currently favorable to which income profiles. They know which automated underwriting systems will likely flag your application and which lenders use manual underwriting processes where a person actually reads the full picture.
What to ask any broker before committing:
How many self-employed borrowers did you work with in the past 12 months? Which loan types do you most commonly place for freelancers? Do you have access to Non-QM and bank statement products? Have you worked with borrowers whose income structure looks similar to mine? What does your fee structure look like and how are you compensated by lenders?
That last question matters because brokers may be compensated by lenders, by the borrower, or both. Understanding the compensation structure helps you assess whether the products being recommended are the best fit for you.
How to Get a Mortgage When Self-Employed: A Step by Step Process for 2026
Here is a step-by-step process for getting a mortgage when self-employed, from checking your credit reports through closing.
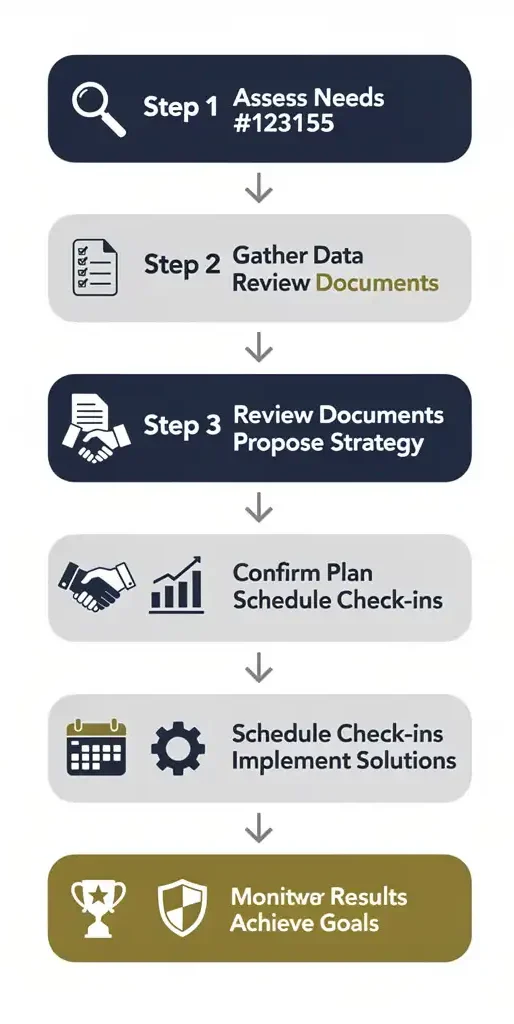
Step 1: Pull all three of your credit reports right now.
Visit AnnualCreditReport.com and download your complete reports from Experian, Equifax, and TransUnion. Do not just check your score on one app. Look at the actual detailed reports for errors, incorrect account information, outdated collections, and anything that does not belong there. Dispute every error you find. Start this process at least six months before you plan to apply.
Step 2: Organize two years of complete tax returns.
Pull your federal returns including every schedule for the last two years. Confirm they are filed and accurate. If your most recent tax year has not been filed yet, consider whether accelerating that filing makes sense before you approach any lender. Many lenders will not process an application without your most recently filed return.
Step 3: Realistically estimate your qualifying income.
Estimate your qualifying income using a cash-flow and trend analysis of your tax returns, as described earlier in this guide, rather than simply averaging the last two years. If your income declined in the most recent year, ask the lender how it will analyze the trend and the reasons for the decline.
Step 4: Collect 12 to 24 months of bank statements.
Even if you believe you will be taking a conventional approach, have these ready. During the underwriting process, paths sometimes shift. Being prepared for multiple documentation approaches saves significant time and prevents delays.
Step 5: Work with a mortgage broker who specializes in self-employed borrowers.
This is the single most important practical step for any freelancer with a complex income situation. A strong specialist broker will review your documentation before formally submitting any application, run a soft credit check that does not affect your score, and honestly tell you which loan types and which specific lenders are most appropriate for your profile as it currently stands. They will also flag any issues that need to be addressed before a formal application goes in.
Step 6: Get pre-approved before house hunting seriously.
A pre-approval tells you your approximate borrowing capacity and shows sellers that a lender has reviewed your finances. Get pre-approved before house hunting seriously so you know your budget and can move quickly when you find a property.
Step 7: Submit your full application once you are under contract on a property.
With organized documentation, a specialist broker’s guidance, and a solid pre-approval in place, the full application process becomes significantly more manageable. Expect underwriters to ask follow-up questions about specific deposits, income sources, or business activities. This is completely normal for self-employed applications and does not indicate a problem.
Step 8: Respond to every underwriter request within 24 to 48 hours.
The single biggest source of unnecessary delays in self-employed mortgage applications is slow responses to document requests. Have your accountant, bookkeeper, and financial records accessible and on standby throughout the underwriting period. Delays in responding compound quickly and can push your closing timeline back significantly.
Step 9: Closing day.
You sign what feels like an unreasonable number of documents, funds transfer, and you receive the keys. This part works exactly the same whether you are employed or freelancing.
Mortgage With 1 Year Self-Employed: Is It Actually Possible?
One of the most common questions appearing in Reddit threads and Quora discussions about self-employed mortgages is some version of: “I just went freelance less than two years ago. Am I completely out of luck?”
No. You are not out of luck. But you need to approach this situation with the right strategy.
Getting a freelancer mortgage with less than two years of self-employment history is genuinely possible in 2026, though it requires the right loan type, the right lender, and typically some stronger compensating factors to offset the shorter documentation history.
Prior industry experience is a powerful argument in your favor. If you spent seven years as a salaried software engineer and transitioned to independent contracting 14 months ago, a knowledgeable underwriter can see that you did not change careers. You changed your employment structure while staying in the same field. Some lenders explicitly allow prior industry experience to be counted alongside your self-employment period when assessing stability.
Bank statement loans are often the most accessible path for newer freelancers. If you have 12 months of strong, consistent deposit history, a number of bank statement lenders will work with that documentation even without a two-year self-employed tax history.
A larger down payment may help compensate for shorter history. A larger down payment reduces the lender’s exposure and may give the lender more flexibility in how it assesses your application, but the amount that helps varies by lender and program, so ask what down payment terms apply to your profile.
A stronger credit profile may help. A long, clean credit history can support your application, but the credit profile a lender requires varies by lender and program, so ask what credit terms apply to your profile.
Working with a specialist broker is especially important in the one-year situation because the lenders willing to accommodate shorter history are not always the most visible ones, and approaching the wrong lender first wastes a credit inquiry.
Self-Employed Mortgage Without Two Years of Tax Returns: Special Situations and Solutions
Let us look specifically at the scenarios where the standard two-year documentation requirement is genuinely challenging and what your realistic options are.
Recently Transitioned From Employment to Freelancing
This is perhaps the most common situation. You left a traditional job, possibly quite a well-paid one, and started freelancing within the last 12 to 18 months. Your income is comparable or better than it was, but your tax history as self-employed is limited.
Your best documentation approach:
Gather your final employment records showing your previous salary and job title. Prepare bank statements from the full period of your freelancing showing consistent client income deposits. Get a CPA to prepare a year-to-date profit and loss statement for your current freelancing activity. Emphasize the continuity of your professional field in any cover letters or broker communications.
The bank statement loan category, combined with a specialist broker who can articulate your transition narrative to the right lender, gives you the strongest realistic path in this situation.
Self-Employed Mortgage Down Payment: How Much Do You Actually Need?
Down payment requirements for self-employed mortgage applications vary by program, borrower, and lender. Confirm the current down payment terms for the loan type you are considering before assuming a figure.
Down payment terms vary by program:
Conventional loans: down payment requirements vary by program and borrower; confirm the current program terms. FHA loans: minimum down payment and credit requirements vary; confirm current FHA requirements and any lender overlays. VA loans: many VA-backed loans are made without a down payment, according to VA.gov, but confirm eligibility and lender requirements. Non-QM and bank statement loans: minimum down payment varies by lender and program; confirm the current program terms.
The strategic reality for self-employed borrowers is this:
A larger down payment can reduce your monthly payment and may affect mortgage insurance requirements, depending on the loan type. Ask your lender how a larger down payment would affect your monthly payment and any mortgage insurance on your loan.
If you are currently saving for your down payment, think carefully about whether waiting an additional few months to save more would improve your loan terms enough to justify the delay.
Government programs worth knowing about in 2026:
The FHA loan program, discussed earlier, remains one of the most accessible government-backed paths for self-employed first-time buyers who cannot bring a large down payment. VA loans continue to offer the zero down option for eligible service members. Various state-level housing finance agency programs offer down payment assistance that can sometimes be layered with FHA or conventional loans. Check your specific state’s housing finance agency for current programs available in your area.
Freelancer Income Verification Mortgage: Building the Strongest Possible Document Package
Freelancer income verification for a mortgage goes beyond simply gathering documents. It is about presenting a coherent, consistent financial narrative that a lender or underwriter can follow clearly without confusion or gaps.
Here is how to build that narrative deliberately.
Consistency across all documents is non-negotiable. Your 1099 totals should align logically with your tax return income. Your bank deposit history should tell a story consistent with your stated client income. Your CPA-prepared profit and loss statement should reflect patterns visible in your banking activity. When these documents tell conflicting stories, even accidentally, underwriters flag the discrepancy and the questions multiply.
Gaps in income need context, not concealment. If you had a quiet quarter during which a major client delayed a large invoice, or if you took three months off for a health matter, document it. A brief explanatory letter from you or a note from your accountant addressing a specific gap is far better than an underwriter sitting with unanswered questions about why your deposits dropped significantly for three months.
Separation of business and personal finances makes everything cleaner. A dedicated business bank account means your business income is clearly traceable without personal transactions muddying the picture. This is valuable both for bank statement loan documentation and for the general clarity of your financial records when an underwriter reviews them.
An accountant who understands mortgage applications is a strategic asset. Some CPAs specifically have experience preparing self-employed clients for mortgage applications. They know which line items lenders scrutinize, they understand the add-back policies for non-cash deductions, and they can prepare supplementary documentation like projections letters or income trend analyses that some lenders will consider as supporting evidence.
Freelancer Mortgage Mistakes That Kill Applications Before They Start
Here are the most damaging mistakes to avoid before you apply.
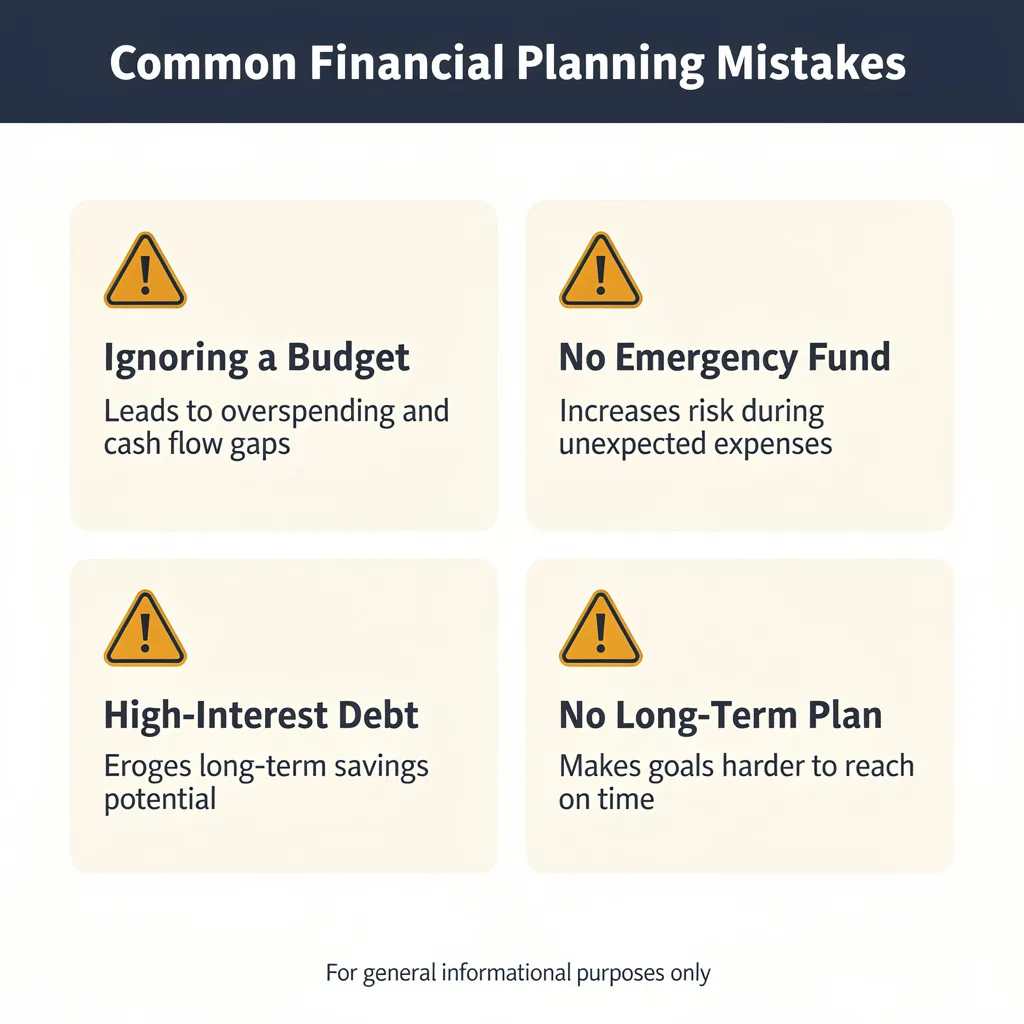
Applying to the Wrong Lender First and Taking a Hard Credit Inquiry
Every formal mortgage application triggers a hard credit inquiry that shows up on your credit file and can affect your score. If you apply to a lender who was never going to approve you due to their rigid self-employed income criteria, you have taken a credit score hit for nothing and your application history now includes a declined file.
A specialist broker running a soft pre-assessment before any formal application can help you avoid applying to a lender that was never a good fit, which reduces the risk of an unnecessary hard inquiry.
Inconsistent Documentation That Raises Red Flag Questions
Lenders cross-reference extensively. Your 1099 forms against your tax return. Your tax return against your bank statements. Your bank statements against your stated monthly income. Your company accounts against your personal income declarations.
If these documents tell inconsistent stories, even for explainable reasons, underwriters pause the file and ask questions. Enough questions means delays. Enough delays or unresolved discrepancies means denial.
Build your document package so that everything tells a consistent, coherent story before a single piece of it reaches a lender’s desk.
Over-Optimizing Tax Write-Offs in the Years Before Your Application
This is the core freelancer mortgage tension and there is no single right answer. Claiming every legitimate deduction minimizes your tax liability, which is smart financial behavior. But those deductions reduce the net income figure that conventional lenders use to calculate your borrowing capacity.
If you are planning a mortgage application within one to two years, have a specific conversation with your accountant about this balance. Some freelancers choose to be more conservative with borderline deductions in the tax years they plan to use for mortgage documentation. This is legitimate tax strategy applied with your full financial goals in mind, not gaming the system in any problematic sense.
For freelancers who have already heavily optimized their deductions, bank statement loans or 1099 loans offer the path around this challenge.
Changing Your Business Structure Right Before Applying
Moving from a sole proprietorship to an LLC, from an LLC to an S-Corporation, or making any significant structural change to how your business is organized right before a mortgage application effectively resets your business history clock from the lender’s perspective.
You might have been operating productively and profitably for six years, but if you incorporated three months ago, some underwriting systems will treat your LLC as a three-month-old entity.
Plan any structural changes at least one to two years before you want to apply for a mortgage. If you are considering restructuring for tax efficiency, allow time for the new structure’s history to build before you apply.
Assuming One Rejection Is a Final Verdict on Your Borrowing Eligibility
A rejection from one lender, particularly a mainstream one with automated underwriting, is information about that specific lender’s criteria. It is not a universal judgment on your creditworthiness.
A borrower turned down by one lender may still be approved by another lender with different underwriting criteria, so a single rejection does not describe every lender’s assessment.
One no is a redirect. It is not a verdict.
How to Improve Your Freelancer Mortgage Chances: Practical Steps That Work in 2026
Beyond avoiding mistakes, here are proactive actions that genuinely move the needle.
Build a substantial cash reserve above and beyond your down payment. Having accessible savings beyond the down payment and closing costs demonstrates stability to lenders; ask your lender what reserve amount it expects for your loan type.
Reduce existing debt before applying. Every dollar of monthly debt payment you eliminate improves your debt to income ratio. Pay down credit card balances, since lower balances can also help your credit profile.
Maintain a diversified and stable client base. Heading into a mortgage application with income coming from multiple established clients looks more stable than relying heavily on one large project or one primary client relationship. Diversified income sources signal business resilience to an underwriter.
Separate your business and personal finances completely. If you are not already using a dedicated business checking account, open one before you apply. Clean financial separation makes your income traceable and your documentation credible.
Update your address records across all accounts. Address consistency across your credit file, tax documents, bank accounts, and mortgage application helps lenders verify your identity and history.
Consider working with an accountant who understands the mortgage context. A good accountant for a self-employed homebuyer prospect is not just someone who minimizes your tax bill. They understand the balance between tax efficiency and mortgage eligibility, they can prepare clear and lender-appropriate documentation, and they can write a strong accountant’s reference letter when a lender requests one.
Mortgage Protection Insurance: The Coverage Freelancers Cannot Afford to Overlook
One thing that comes up consistently in the mortgage process that freelancers routinely underestimate: the absence of employment-based financial protection once you become a homeowner.
When you work for an employer, you typically have access to disability insurance, paid sick leave, and sometimes life insurance or death-in-service benefits. These protections exist specifically to ensure you can continue meeting financial obligations if something goes wrong with your health or your life.
As a freelancer, you have none of these automatically. If you were ill or injured and unable to work for three months, your mortgage payment still arrives on exactly the same schedule it always did.
Income protection insurance replaces a defined proportion of your income if you are genuinely unable to work due to illness or injury. The proportion covered and the terms vary by policy, so compare policies before relying on a figure.
Mortgage protection life insurance pays out an amount sufficient to cover your outstanding mortgage balance in the event of your death. Many policies are structured so the coverage amount decreases over time in line with your reducing mortgage balance.
Critical illness cover provides a lump sum payment upon diagnosis of specific serious illnesses. For a freelancer whose income would stop immediately with a serious diagnosis, this coverage can protect both the mortgage and the broader financial stability of the household.
These products are distinct from your mortgage but should be considered alongside it as part of your complete financial picture as a self-employed homeowner.
Using Technology to Make Your Mortgage Application Smoother
Being organized is a competitive advantage in the self-employed mortgage process. The right tools make that organization significantly easier to maintain.
Accounting software creates the clean financial records that support mortgage applications. QuickBooks Self-Employed, FreshBooks, and Wave are all solid choices for freelancers who want organized, consistent financial records. When your profit and loss data is cleanly maintained throughout the year, producing documentation for a mortgage application becomes a matter of extraction rather than reconstruction.
Separate business banking platforms streamline everything. Relay, Mercury, and Novo are business banking options that work well for freelancers and produce clean, detailed statements with clear transaction descriptions. This makes bank statement loan documentation far more straightforward than personal accounts often can be.
NMLS Consumer Access at nmlsconsumeraccess.org allows you to verify that any lender or broker you are considering is properly licensed in your state. Never work with an unlicensed mortgage professional regardless of how persuasive their pitch sounds.
Authorized bank-data sharing is increasingly relevant in 2026. Some lenders now accept authorized read-only access to your transaction data to verify income and deposits, where the lender offers that option. Ask your lender whether it offers this kind of data sharing and what access it requires.
Self-Employed Mortgage Application Checklist: Everything Organized in One Place
Use this as your complete reference before submitting anything.
Conventional: Two years of complete federal tax returns with all schedules. Business tax returns only where the lender requires them for your business type; confirm the exceptions described earlier in this guide. Two to three months of personal bank statements, government-issued photo identification, and proof of down payment funds.
FHA: Two years of tax returns and income documentation similar to conventional loans, plus confirmation of current FHA credit, down payment, and mortgage insurance requirements with an FHA-approved lender, since lender overlays may apply.
VA: Certificate of Eligibility (COE) showing VA loan entitlement, plus tax returns, bank statements, and documentation of residual income as the lender applies it. Confirm current VA requirements and any lender overlays.
Bank Statement: 12 or 24 months of business and personal bank statements as the program requires, plus identification and down payment documentation. Ask the lender how it treats business expenses and non-recurring deposits when calculating qualifying income.
1099: 1099 forms for the past two years, plus tax returns and bank statements as the program requires. Ask the lender how it applies its own expense rules to gross 1099 income when calculating qualifying income.
Asset Depletion: Statements for the savings and investment accounts the program counts as eligible assets, plus identification and down payment documentation. Ask the lender which assets count, whether any haircut applies, and what divisor it uses.
Property and Transaction Documents: Accepted purchase offer or sales contract once you are under contract, plus any landlord or rental history documentation the lender requests.
Hypothetical conventional worked example (illustration only, not a guarantee): a sole proprietor reports net Schedule C income of $72,000 in year one and $84,000 in year two, with no business-entity returns. Under a cash-flow and trend analysis, the lender reviews both years and the trend rather than simply averaging them; the qualifying income it uses depends on its analysis of the trend, the stability of the income, and its current program rules, so confirm the calculation with your lender before assuming a borrowing amount.
Frequently Asked Questions About Freelancer Mortgages in 2026
Can a freelancer get a mortgage?
Yes. Freelancers can qualify for conventional, FHA, VA, bank statement, 1099, and asset depletion loans. The key is matching your specific income documentation to the right loan type and lender through a specialist broker.
How do freelancers prove income for a mortgage?
Through two years of federal tax returns, 1099 forms, bank statements, and CPA-prepared profit and loss statements. For bank statement loans, 12 to 24 months of deposit history replaces tax returns as the primary income verification.
How many years do you need to be self-employed to get a mortgage?
Most lenders require two years. Some bank statement lenders and specialty products work with 12 months of history when compensating factors like a high credit score, large down payment, or strong prior industry experience are present.
How much can a freelancer borrow for a mortgage?
This depends on your verified qualifying income, credit score, debt to income ratio, and down payment amount. Maximum debt-to-income ratios vary by lender and program, so ask a lender for its current limit. A specialist broker can calculate specific numbers based on your actual documentation.
Can I get a mortgage with one year of self-employment?
Yes, in some cases. Bank statement loans, specialty Non-QM products, and FHA loans with strong compensating factors can accommodate one year of self-employment history, particularly with prior professional experience in the same field.
Do freelancers get rejected for mortgages more often?
Freelancers face higher rejection rates at mainstream automated underwriting systems. However, many of those rejections are resolved by working with a specialist broker to identify appropriate lenders. A rejection from one institution is not a final verdict.
What is the best mortgage for a freelancer who claims lots of deductions?
Bank statement loans or 1099 loans, because these qualify you based on actual cash flow or gross 1099 income rather than net taxable income after deductions. These Non-QM products were built specifically for this situation.
Is it harder to get a mortgage as a freelancer?
The process requires more documentation and more strategic lender selection than a W-2 application. For a freelancer with two or more years of consistent income, good credit, and proper preparation, approval is genuinely achievable through the right channels.
What credit score do I need for a freelancer mortgage?
Credit requirements vary by program and lender. Conventional, FHA, and Non-QM programs each set their own credit requirements, and individual lenders may apply additional requirements, so confirm the current requirements for the loan type you are considering.
Should a freelancer use a broker or go direct to a lender?
A broker who specializes in self-employed borrowers can be a strong choice, because they can shop your application across lenders with different underwriting criteria. Compare brokers on their experience with self-employed borrowers and their fee and compensation structure before committing.
Final Thoughts on Freelancer Mortgages in 2026
This guide covers the documents, loan types, and questions that matter most for self-employed borrowers.
The freelancer mortgage process is harder than it needs to be. The system genuinely was not built for people who work independently, and navigating something that was not built for you requires more preparation and more strategic thinking than following the standard path.
But here is what I want you to hold onto from everything you have read here.
Your income structure is not a liability. It is just a different kind of asset that requires the right interpreter to be properly understood.
The right broker who works with self-employed clients regularly. The right loan type that matches how your income actually appears on paper. The right lender whose underwriting criteria were built with your situation in mind. The right documentation prepared clearly and presented consistently.
Those four things together can make the freelancer mortgage process clearer and more manageable.
Start with your credit reports. Organize your tax documents. Find a specialist broker before you start property hunting. And do not let one rejection from one institution with one rigid automated system tell you something untrue about your ability to own a home.
You have already built something sustainable enough that you are in a position to want to buy a house. That is genuinely not easy. The mortgage process will test your patience. But the foundation, a real career with real income that you built entirely for yourself, is already there.
Now go find the people who can see that clearly.
This article is written from personal experience and provided for general informational and educational purposes only. It does not constitute professional financial, tax, or legal advice. Mortgage products, eligibility requirements, lender criteria, and interest rates change frequently. Always consult with a licensed mortgage professional or qualified financial advisor before making decisions related to any mortgage or home purchase. For official US income documentation guidance, visit IRS.gov. For consumer financial protection resources, visit ConsumerFinance.gov.


