
Us bank business accounts changed my financial life in a way I never expected. I am not exaggerating even slightly. Before I opened a dedicated business account through U.S. Bank, operated by U.S. Bancorp, my finances were a complete disaster. Every Monday morning I would open my personal banking app, stare at one single account filled with client payments, grocery charges, Netflix subscriptions, and random Amazon purchases, and I would feel this immediate wave of cold panic move through my chest. I could not tell if I was profitable. I could not tell what I owed in taxes. I could not tell anything at all.
That panic is real. And if you are a freelancer reading this right now, I am willing to bet you have felt exactly that same feeling.
The good news? There is a very clean, very practical fix.
Opening a dedicated us bank business account for your freelance work creates an immediate, sharp separation between your personal financial life and your professional one. It is one of the best decisions I ever made, and it took less time to set up than I expected. This complete guide covers everything you actually need to know in 2026. The account tiers. The fees. The exact documents you need. The tricks to waive monthly fees. And the honest truth about where U.S. Bank excels and where it falls short.
I pull no punches here.
Why Us Bank Business Accounts Are Not Just for Big Companies
Us bank business accounts serve freelancers, solo operators, and single-person LLCs just as effectively as they serve established companies with dozens of employees.
I used to think the phrase “business account” meant something formal and corporate. I pictured a man in a gray suit sitting across from a bank manager inside a glass office. I pictured stacks of financial reports and complicated approval processes. That picture is completely wrong.
When I finally walked into my local U.S. Bank branch back in 2022, the process was shockingly simple. The banker asked me a few questions, looked at my documents, and had me set up with a functioning business checking account in about 45 minutes. She told me that the majority of their business account customers are exactly like me. Solo freelancers. Independent contractors. Small shop owners. Single-person LLCs.
You do not need a massive revenue stream. You do not need a legal team. You just need to treat your work like the real business it actually is.
And here is something important that a lot of freelancers miss completely.
The Internal Revenue Service does not care whether you feel like a real business. If you earn money from independent work, you are legally operating a business. The way you manage those earnings directly affects how much stress you experience every April when estimated tax payments come due or when you file your annual return.
Mixing personal and business money creates what accountants call a “commingled funds” situation, which makes record-keeping harder at tax time. Keeping business money separate helps you track income and expenses cleanly.
So whether you are a freelance writer, a graphic designer, a consultant, a photographer, or anyone who receives payment for a service, a dedicated us bank business account is not optional. It is a foundation.
The freelance economy is large, and many independent workers earn income outside traditional employment. The right banking setup is the first piece of that financial infrastructure.
Here is a specific thing I noticed when I moved my freelance income into a dedicated business account. My invoices looked more professional immediately. Clients could make payments directly to a business entity rather than a personal name. And when I sat down to do my quarterly tax estimates, everything I needed was already organized inside one clean account. No sorting. No guessing. No panic.
That alone was worth every cent of any fee.
US Bank Business Checking Account: Every Tier Explained for 2026
The U.S. Bank business checking lineup shown on U.S. Bank’s current checking page is Business Essentials, Gold Business Checking, Platinum Business Checking, Premium Business Checking, and Nonprofit Checking. Silver Business Checking is not shown on that page, so it is not presented here as a current option; see the note on Silver below. All checking accounts open with a $25 minimum deposit, and no checking package offers unlimited transactions of every kind.
This is where most people get confused. They land on the U.S. Bank website and see a wall of account options and feel immediately overwhelmed. I am going to break this down in the simplest possible way.
Think of the account tiers as a staircase. At the bottom step, you have the entry-level option built for freelancers and brand new businesses. Higher steps add larger transaction allowances and different fee structures. Your job is to figure out which step you are standing on right now.
US Bank Business Essentials: The Freelancer’s Starting Point
The US Bank Business Essentials account launched officially in April 2025, and it represented a real shift in how the bank approaches small business customers. This is not a stripped-down, bare-bones account that makes you feel like a second-class customer. It is an all-in-one solution that includes business checking features, the ability to accept card payments, and basic tools to manage your cash flow.
Here are the core details you need to know for 2026.
There is no monthly maintenance fee: Business Essentials is $0 flat, with unlimited digital transactions and 25 free teller and paper transactions per statement cycle. The account comes with a U.S. Bank Visa debit card for business purchases. You get access to the full online banking dashboard and the mobile banking app. And crucially for freelancers who take payments from clients, the account integrates card payment acceptance capabilities. Note: the “six qualifying transactions” figure relates to the $400 new-account bonus promotion (with a $5,000 deposit and balance condition), not to keeping the monthly fee at $0.
That last feature matters more than most people realize. When a client pays your invoice and the money settles in your account the same day, your cash flow management improves. Same-day funding itself is free, but card acceptance is not free: Business Essentials processing is 2.60% + $0.10 for tap/insert, 3.50% + $0.15 for keyed, and 2.90% + $0.30 online, plus a $35 chargeback fee.
For most solo freelancers in 2026, the Business Essentials account is the answer.

US Bank Silver Business Checking: Availability Uncertain — Do Not Treat as a Current Option
Silver Business Checking is priced in U.S. Bank’s August 10, 2026 Business Pricing Information brochure, but it does not appear on U.S. Bank’s current business checking page — neither in the account cards nor in the compare tool. Its current availability for new accounts therefore could not be confirmed, and it is presented here as legacy/uncertain, not as a current option. Do not choose it on the basis of this guide alone; confirm with a U.S. Bank banker whether new Silver accounts are offered.
The brochure prices Silver at $0 flat — there is no monthly maintenance fee to waive and no waiver balance to meet. That corrects the earlier claim that Silver carried a waivable fee. Because its current availability is uncertain, no Silver fee scenario is presented as a current recommendation.
If you already hold a Silver account, check your own pricing disclosure and ask a banker whether your terms have changed, rather than assuming the current checking page applies to you.
US Bank Gold Business Checking: For Growing Operations
The U.S. Bank Gold Business Checking package is built for businesses that have moved beyond the entry level. It costs $20 per month, or $0 when a waiver requirement is met, and includes 350 free transactions per statement cycle, with $0.45 for each additional transaction and 125 free cash deposit units per statement cycle.
Gold’s monthly fee can be waived with U.S. Bank Payment Solutions, or a $10,000 average collected account balance, or $20,000 combined average collected balances across U.S. Bank business deposit accounts, or $50,000 combined average collected balances and outstanding credit balances.
For the average freelancer, the Gold account is probably more account than you need in 2026 unless your client roster has grown substantially or you have added team members.
US Bank Platinum Business Checking: The Power User Account
The U.S. Bank Platinum Business Checking package is a high-volume option, but it is not the top of the lineup: the Premium Business Checking Package sits above it at $34 per month. Platinum includes 550 free transactions per statement cycle, with $0.40 for each additional transaction and 250 free cash deposit units per statement cycle.
Monthly maintenance fees on Platinum are $30 per month, or $0 when a waiver requirement is met: U.S. Bank Payment Solutions, or a $25,000 average collected account balance, or $75,000 combined average collected balances across U.S. Bank business deposit accounts and outstanding business credit balances.
Most freelancers will not need Platinum. But if you have scaled your operation to the point where you are regularly processing high volumes of payments, managing payroll for a small team, and moving substantial funds through wire transfers, it is worth a conversation with a business banker.
The Nonprofit Checking Account: A Special Mention
U.S. Bank also offers a Nonprofit Checking Account specifically designed for registered nonprofit organizations. It is $0 per month, with 1,800 free transactions per calendar year and $0.50 for each additional transaction. If your freelance work is structured through a nonprofit entity, discuss its requirements directly with a branch representative.
US Bank Business Savings Account: Building Your Tax and Emergency Buffer
The US Bank business savings account lets freelancers separate and grow reserve funds for taxes, slow months, and emergency operating expenses, with FDIC insured deposits starting at a $25 minimum opening deposit.
Here is my honest confession.
The first two years I freelanced, I paid my taxes in a state of absolute dread every single quarter. I would look at what I owed, realize I had not set enough aside, and scramble to cover the difference. It was embarrassing. It was stressful. And it was completely preventable.
The U.S. Bank business savings account is not a glamorous product. It does not offer jaw-dropping interest rates. But that is not actually what it is for when you are a freelancer. The savings account serves as a behavioral separation tool. It creates a physical and psychological barrier between your operating funds and your reserve funds.
When money goes into that savings account, the rule I follow is simple. It does not come back out unless it is going directly to a tax payment or covering a genuine emergency that threatens my ability to operate.
The FDIC insurance on business savings accounts at U.S. Bank covers deposits up to $250,000, which is the standard protection provided through the Federal Deposit Insurance Corporation. For freelancers, this means your reserve funds are federally protected even if something happened to the bank itself. That is a meaningful layer of security for money you are counting on to cover your tax obligations.
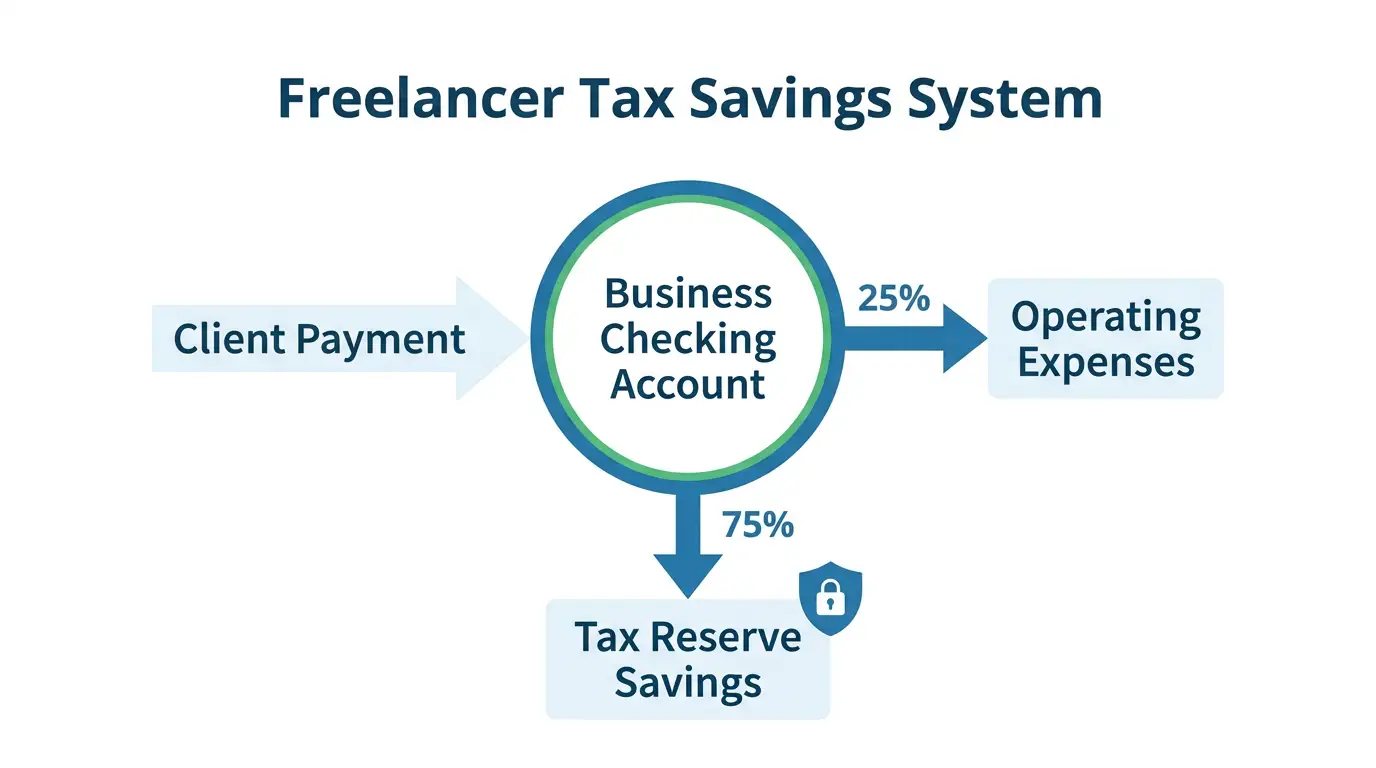
The automation feature inside U.S. Bank’s online banking portal allows you to set up recurring transfers from your business checking account to your business savings account. I have mine set to transfer a fixed percentage of any incoming deposit automatically within 24 hours of receipt. I honestly never think about it anymore. The buffer builds itself while I focus on client work.
A practical number to start with: Most tax professionals recommend that self-employed individuals in the United States set aside between 25 and 30 percent of every payment received for federal and state tax obligations. If you are in a higher income bracket, that number can climb closer to 35 percent. Using your business savings account as the automatic holding tank for that percentage transforms tax season from a crisis into a routine payment.
The minimum opening deposit for the business savings account is just $25. That is an accessible entry point for anyone, regardless of where they are in their freelance journey.
US Bank Business Account Fees: The Full, Honest Breakdown
U.S. Bank business account fees range from $0 per month for Business Essentials up to $34 per month for the Premium Business Checking Package, which sits above Platinum. All checking accounts open with a $25 minimum deposit. The table below is dated to U.S. Bank’s pricing effective August 10, 2026; confirm current pricing before applying, as fees can change.
I want to be real with you here.
Fee structures at large banks are intentionally complicated. Not in a malicious way, necessarily, but in a way that benefits the bank if you do not read the fine print carefully. I spent a significant amount of time digging through U.S. Bank’s actual fee schedules, and I am going to translate the important parts into plain language.
US Bank Business Account Monthly Fee: Tier by Tier
Dated fee and eligibility table (pricing effective August 10, 2026): Business Essentials — $0 flat monthly fee, unlimited digital transactions, 25 free teller and paper transactions per statement cycle. Gold Business Checking — $20 per month, or $0 with U.S. Bank Payment Solutions or a $10,000 average collected account balance, or $20,000 combined average collected balances across business deposit accounts, or $50,000 combined average collected balances and outstanding credit balances; 350 free transactions, then $0.45 each; 125 free cash deposit units. Platinum Business Checking — $30 per month, or $0 with U.S. Bank Payment Solutions or a $25,000 average collected account balance, or $75,000 combined average collected balances across business deposit accounts and outstanding business credit balances; 550 free transactions, then $0.40 each; 250 free cash deposit units. Premium Business Checking — $34 per month, with fees offset through an earnings credit based on balance. Nonprofit Checking — $0 per month, 1,800 free transactions per calendar year, then $0.50 each. Silver Business Checking — $0 flat in the brochure, but its current availability for new accounts could not be confirmed (see the Silver note above), so it is not listed as a current option. Cash deposit units above the free allowance are $0.35 per $100. No checking package offers unlimited transactions of every kind.
Sources: U.S. Bank Premium Business Checking Account Package and Platinum Business Checking Account Package product pages. Fees in the table above are from the August 10, 2026 brochure; confirm current pricing on the official pages before applying.
Cost scenarios (illustrative, before any other fees): A solo freelancer on Business Essentials with digital transactions only pays $0 in monthly maintenance fees. A Gold account with 400 transactions in a month and no waiver pays $20 plus 50 x $0.45 = $22.50 in excess transaction fees, for $42.50 that month; with a waiver met, the same month costs $22.50 in excess fees. A Platinum account with 600 transactions in a month and no waiver pays $30 plus 50 x $0.40 = $20.00 in excess fees, for $50.00 that month; with a waiver met, the same month costs $20.00 in excess fees. The key point: not every tier has a simple waiver path — Essentials and Nonprofit are $0 flat, Premium is offset by an earnings credit, and Gold and Platinum waivers depend on the balances or Payment Solutions use listed above.
US Bank Business Account Transaction Limits and Per-Item Fees
This is the area where business bank accounts most often catch people off guard.
Every checking account tier includes a set number of free transactions per month, except that Business Essentials offers unlimited digital transactions (with 25 free teller and paper transactions per statement cycle). Once you exceed the free allowance, Gold charges $0.45, Platinum $0.40, and Nonprofit $0.50 per additional transaction. No package offers unlimited transactions of every kind.
For freelancers who primarily receive a handful of client payments per month and use the account to pay a small number of business expenses, the Business Essentials digital transaction allowance is more than sufficient. You will not hit the ceiling.
But if you start processing dozens of transactions per week, it is worth doing a quick monthly transaction count and comparing it against the free transaction allowance in your current tier.
US Bank Business Account Wire Transfer Fees
Wire transfers carry their own separate fee schedule at U.S. Bank.
Domestic outgoing wire transfers cost $30 digital, $40 at a branch, and $45-$50 by voice. Incoming domestic wire transfers cost $14-$16. International outgoing wire transfers cost $45 digital in USD and $75 for foreign-exchange wires. The earlier $20-$30 domestic outgoing range is therefore replaced by these figures.
If international wire transfers are a regular part of your freelance work, meaning you are paying international vendors or receiving payments from international clients, it is worth calculating the monthly cost of those wires and factoring that into your account tier decision.
Cash Deposit Fees
Most freelancers do not deal with physical cash regularly. But if you do, U.S. Bank charges fees for cash deposits above a free cash deposit unit allowance: Gold includes 125 free cash deposit units and Platinum includes 250 free cash deposit units per statement cycle, with $0.35 per $100 above the allowance. Business Essentials’ 25 free teller and paper transactions per statement cycle is a separate transaction limit, not a cash deposit unit allowance. If you regularly deposit cash from in-person client payments or retail sales, pay attention to this line item.
Overdraft Protection Service
U.S. Bank offers overdraft protection as an optional service on business checking accounts. You can link a backup account or a line of credit to cover transactions that would otherwise overdraft your balance. There are fees associated with this service depending on how it is triggered and which backup source you use.
My personal recommendation: do not rely on overdraft protection as a regular cash flow management tool. Use it as a true emergency backstop and focus instead on maintaining a buffer in your checking account that keeps you well above zero at all times.
US Bank Small Business Banking: Is the Ecosystem Worth It?
US Bank small business banking in 2026 extends far beyond checking accounts, offering an integrated ecosystem that includes credit cards, merchant services, business loans, payroll tools, and a highly rated mobile banking app.
This is the part that actually surprised me when I got deeper into my relationship with U.S. Bank.
I opened a basic business checking account expecting nothing more than a place to receive payments and pay expenses. What I found was a fairly comprehensive small business banking platform that I could grow into as my freelance operation expanded.
The US Bank Business Debit Card
The business Visa debit card that comes with your checking account is more than just a payment card. It gives you a clean, professional way to pay for business expenses that creates an automatic, organized digital record inside your account statement. Every software subscription, every business-related supply purchase, every professional membership fee shows up in your business account history without any manual sorting.
That organized expense history becomes incredibly valuable at tax time. Your accountant or your tax software can import a clean transaction history from a dedicated business account. No commingled personal charges to sort through.
US Bank Business Account Online Access and Mobile Banking
The online banking portal for U.S. Bank business customers is genuinely well-designed in 2026. It gives you a 360 degree view of all connected accounts, including checking, savings, and credit products. You can initiate ACH transfers, pay bills, manage payroll integrations, set up automatic savings transfers, and download statements directly.
The mobile banking app carries high ratings across both major app stores in 2026. It supports mobile check deposit, which is particularly useful for freelancers who still receive occasional paper checks from clients. The app also supports Zelle for business, which in 2026 has become a standard payment method for small business-to-business transactions and client payments.
A note on multi-user business banking access: The U.S. Bank Shared Access feature allows business owners to grant specific levels of access to the account to other people, such as a bookkeeper or an accountant, without sharing full account control. This feature becomes useful as your freelance operation grows and you bring in support roles.
US Bank Merchant Services Business Integration
If your freelance work involves accepting in-person card payments, U.S. Bank’s merchant services integration through the Business Essentials account is genuinely competitive. Same-day funding means client card payments settle to your business account the same day the transaction is processed, but card acceptance itself is not free: processing is 2.60% + $0.10 for tap/insert, 3.50% + $0.15 for keyed, and 2.90% + $0.30 online, plus a $35 chargeback fee.
This eliminates a common pain point for freelancers who invoice clients and wait for payment to clear. Same-day funding improves cash flow management significantly for anyone who operates on a tight monthly budget.
US Bank Business Account Credit Card Options
U.S. Bank offers several business credit cards that integrate cleanly with your business checking account. The ability to manage both your credit card activity and your checking account within a single banking dashboard simplifies expense tracking and statement reconciliation.
Some U.S. Bank business credit cards offer cash back rewards on specific business spending categories, which can meaningfully reduce net operating costs over the course of a year. Whether a business credit card makes sense for your freelance operation depends on your spending patterns and your ability to pay the balance in full each month.
US Bank Business Account Fraud Protection
Fraud protection on business accounts is a topic that does not get enough attention in most banking guides.
U.S. Bank implements BSA and AML compliance standards across all business accounts, which are regulatory requirements under federal banking law. Beyond those baseline protections, the bank offers proactive fraud monitoring, real-time transaction alerts through the mobile app, and the ability to set custom transaction controls on your business debit card.
In 2026, with digital banking fraud at historically high levels according to Federal Reserve reports on payment system security, these fraud tools are not a nice-to-have feature. They are a necessity.
US Bank Business Account Requirements: What You Actually Need to Gather
US Bank business account requirements in 2026 vary based on your business structure, but most sole proprietors and single-member LLC owners can open an account with just a few standard documents.
This is the section that causes the most unnecessary anxiety among freelancers.
People read “business account requirements” and immediately picture a stack of notarized legal documents, certified financial statements, and months of business history. That picture is completely disconnected from reality, at least for most freelancers.
Let me walk you through the actual requirements based on business structure.
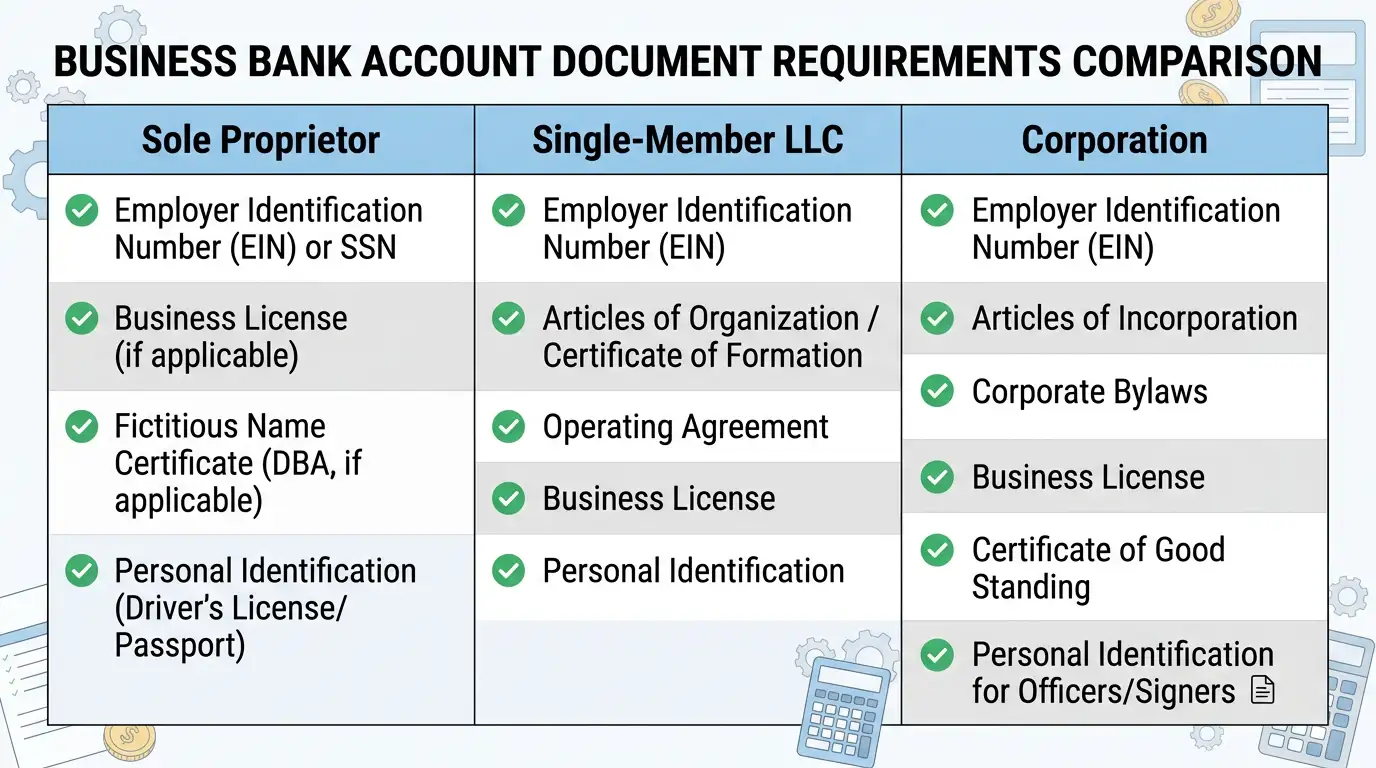
Documents for Sole Proprietors
If you freelance under your own legal name without forming a separate business entity, you are operating as a sole proprietor.
The U.S. Bank business account requirements checklist for sole proprietors is short.
You need a government-issued photo ID. Your driver’s license or passport works perfectly. You need your Social Security Number or, if you have applied for one, your Employer Identification Number. You may need a Doing Business As certificate if you operate under a business name that differs from your personal legal name. Some branches also request a utility bill or document showing your business address, though this varies by location and account type.
That is essentially the complete list for a sole proprietor. No business tax returns. No financial statements. No proof of revenue.
Documents for LLCs
Single-member LLCs are the most common formal business structure among freelancers in the United States.
For an LLC, U.S. Bank requires your government-issued photo ID, your Employer Identification Number (your EIN, which you obtain from the IRS at no cost through their online application system), your Articles of Organization or Certificate of Formation filed with your state, and your Operating Agreement if your LLC has one.
Getting your EIN is a simple process. You apply directly through the IRS website, answer a short questionnaire, and receive it. U.S. Bank’s own guidance is clear, however: an EIN alone typically isn’t enough to open a business bank account. You may also need a government-issued ID, business formation documents, and other information based on your business structure.
Keep all of your LLC formation documents in one organized folder, either physical or digital. You will reference these documents repeatedly throughout the life of your business, not just for banking purposes.
Documents for Corporations
If you have formed a formal corporation (C-Corp or S-Corp) for your freelance operation, the documentation requirements are more extensive. U.S. Bank will want to see your Articles of Incorporation, a corporate resolution authorizing the opening of the account, a list of authorized signers, and your EIN.
For most independent freelancers, a corporation structure is overkill. But if you have formed one for specific legal or tax reasons, your attorney or accountant who helped you structure the entity will have all of these documents readily accessible.
Can You Open a US Bank Business Account Online?
Yes. U.S. Bank allows online business account applications for many account types and business structures in 2026. The Business Essentials account, in particular, is designed for digital onboarding.
The online application process walks you through document submission, identity verification, and initial funding. For most sole proprietors and single-member LLCs, the online path is completely viable.
That said, some business structures and certain situations still require an in-person branch visit. If you have a more complex ownership structure, if you are opening an account under a corporation with multiple authorized signers, or if there are questions during the identity verification process, a branch visit will be necessary.
Double-check that the address you use on your application matches your registered business address exactly before you submit, as mismatches can delay online verification. For remote or nonresident opening, there is no published guarantee; confirm with a banker whether your situation can be opened remotely.
US Bank Business Account Review 2026: Real Talk From Real Users
The US bank business account review landscape in 2026 shows genuinely strong ratings for digital features and account variety, with honest criticism focused on fee complexity and occasional customer service inconsistencies.
I believe in reading what actual users say, not just what marketing materials publish. So I spent time reviewing the real experiences that freelancers and small business owners share publicly.
Here is what I found.
What Users Consistently Praise
The mobile banking app receives generally positive feedback from users who value mobile check deposit and account management on the go.
The Business Essentials account launched in April 2025 has generated notably positive early reception in small business communities. The integrated payment acceptance feature and same-day funding are mentioned repeatedly as differentiators compared to what other large banks offer at the entry-level tier.
The branch network is a meaningful advantage. U.S. Bank operates branches across a wide geographic footprint, which matters to freelancers who occasionally need in-person banking services, access to a notary, or face-to-face problem resolution.
What Users Consistently Criticize
I want to be very direct about this.
Some users report frustration with account management and customer service responsiveness. These are individual experiences, not a measured survey, and they deserve honest acknowledgment alongside the positive feedback.
Some users also raise concerns about account freezes, verification holds on deposits, and difficulty reaching knowledgeable customer service representatives by phone.
These are real complaints and they deserve honest acknowledgment.
U.S. Bank is a large institution. At that scale, customer service consistency across many branches and accounts is a genuine operational challenge. Some customers have excellent experiences. Some have poor ones.
The complaints about account freezes and verification holds are worth noting specifically. U.S. Bank, like all federally regulated banks, must comply with Know Your Customer (KYC) regulations and Bank Secrecy Act requirements. Unusual account activity, especially in new accounts, can trigger automated verification holds that feel frustrating and arbitrary from the customer’s perspective but are legally required from the bank’s perspective.
The takeaway from user feedback: U.S. Bank works extremely well for straightforward freelance banking with a predictable, consistent transaction pattern. It works less well for accounts that experience irregular deposit patterns, large sudden transactions, or complex ownership structures.
Community Banks: The Alternative Frequently Mentioned
Some freelancers prefer a local community bank rather than a large national institution. The reasoning often given is that community banks may offer more personalized relationship banking and may be more flexible in resolving issues quickly because you can speak directly with decision-makers rather than call center representatives.
This is fair and worth considering. But community banks often lack the digital banking infrastructure, the app quality, and the geographic flexibility that large banks provide. The right choice depends on what you value most.
US Bank Business Account Interest Rates: What You Can Realistically Earn
US bank business account interest rates in 2026 apply primarily to business savings accounts and money market accounts, with Annual Percentage Yield rates that reflect the broader interest rate environment set by the Federal Reserve.
I want to set realistic expectations here because a lot of freelancers ask about earning interest on their business accounts as though it is going to be a meaningful income source.
The business checking accounts, including Business Essentials, Gold, and Platinum, are not interest-bearing accounts in the traditional sense. They are transactional accounts designed for cash flow management. Silver is not presented as a current option in this guide; see the Silver note above.
Your business savings account may earn interest, but rates change and no rate is stated here; check U.S. Bank’s current business savings terms before relying on interest as income.
For a freelancer using the business savings account primarily as a tax buffer, the interest earned is a pleasant bonus but should not be the primary reason you keep money there. The organizational benefit of having a separate savings bucket far outweighs whatever interest you earn on a few thousand dollars sitting in reserve.
Business money market accounts offered by U.S. Bank may have different terms and higher minimum balance requirements than standard savings accounts. Check current terms before choosing one; no rate is stated here.
Business certificates of deposit (CDs) represent a locked-in option where you commit funds for a specific term. For emergency fund money that you are confident you will not need to access for a defined period, a business CD may be worth comparing with a savings account; check current terms and do not assume a guaranteed higher rate.
How to Open a US Bank Business Account: Step by Step in 2026
You can open a US bank business account online or in person in 2026, with most sole proprietors completing the online application in under 30 minutes when they have their documents ready.
This is the section where I give you the exact, linear process so there are no surprises.
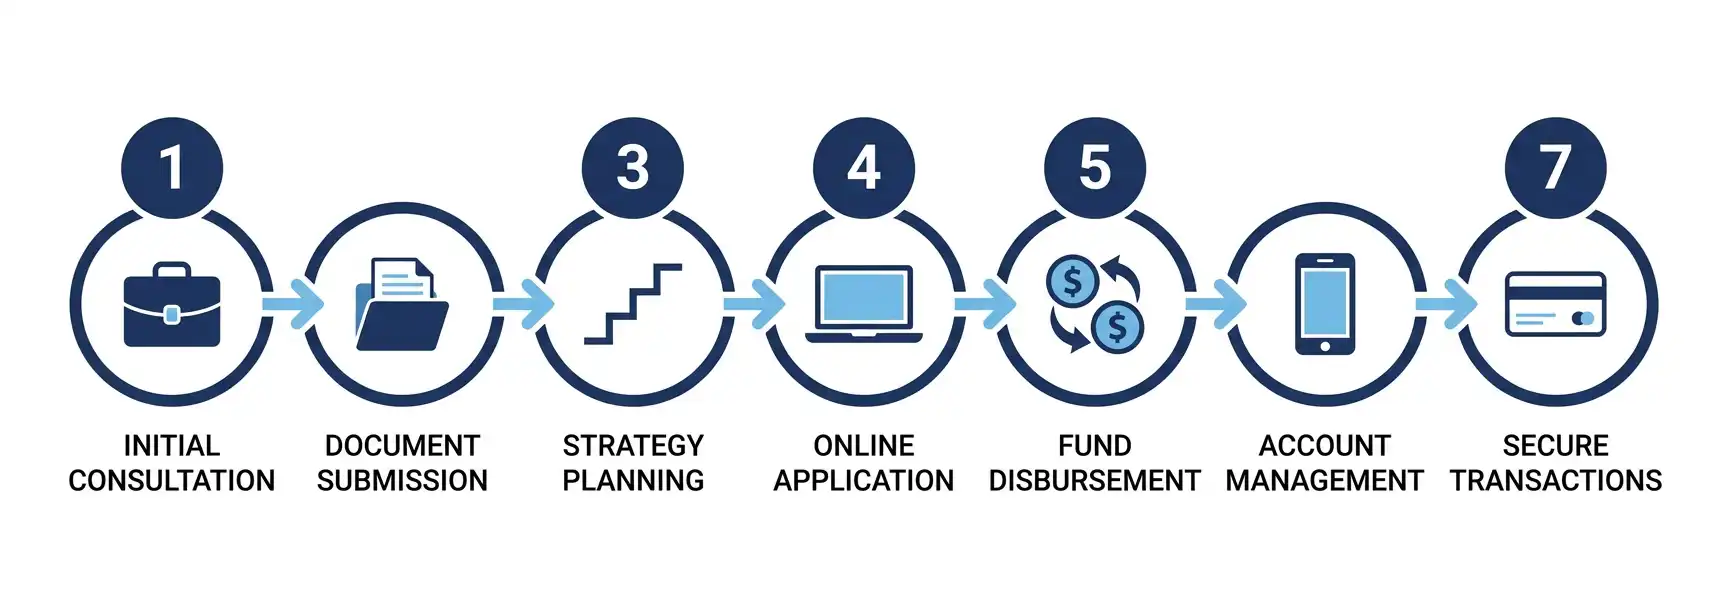
Step 1: Determine your business structure.
Before you do anything else, know whether you are opening the account as a sole proprietor, a single-member LLC, a multi-member LLC, or a corporation. Your structure determines exactly which documents you need.
Step 2: Gather your documents.
For sole proprietors: government-issued photo ID, Social Security Number or EIN, DBA certificate if applicable.
For LLCs: government-issued photo ID, EIN, Articles of Organization, Operating Agreement.
For corporations: government-issued photo ID, EIN, Articles of Incorporation, corporate resolution, list of authorized signers.
Step 3: Choose your account tier.
For the vast majority of freelancers starting out in 2026, the Business Essentials account is the right answer. Do not over-engineer this decision. You can always upgrade your tier later as your business grows.
Step 4: Start the online application at usbank.com or visit a branch.
If you are applying online, navigate to the business banking section and select the account type you want. The online application will prompt you to upload your documents and complete identity verification.
Step 5: Fund your account with an initial deposit. You will need to transfer funds to open the account. U.S. Bank’s checking page states a $25 minimum deposit to open a business checking account.
Step 6: Set up online banking access.
Once your account is open, enroll in online banking through the usbank.com portal. Download the mobile app. Set up your automatic savings transfer to your business savings account. Configure your transaction alerts.
Step 7: Order your business debit card and set up payment acceptance if needed.
Your Visa business debit card arrives within several business days of account opening. If you need to accept card payments from clients, set up the merchant services integration through the Business Essentials platform.
How long does the whole process take?
Online applications for Business Essentials accounts are often approved within one to two business days. In-branch applications are often completed the same day. The physical debit card typically arrives within five to seven business days.
US Bank Business Account Minimum Balance: How to Never Pay a Fee Again
The U.S. Bank business account minimum balance picture varies by tier: Business Essentials and Nonprofit Checking are $0 flat, Gold and Platinum fees can be waived through the balance or Payment Solutions conditions in the fee table, and Premium is offset by an earnings credit. Not every tier has a simple waiver path.
Monthly fees are the thing freelancers fear most about business banking. And the fear is understandable. When you have a slow month with lower than usual client income, the last thing you want is a bank taking an additional $15 or $25 out of your account as a penalty for not being wealthy enough.
The good news is that U.S. Bank designs its fee waiver structures with exactly this concern in mind.
How to Waive the US Bank Business Account Monthly Fee: Each Method Explained
Method 1: Maintain an average daily balance above the required threshold.
Each account tier has a specific average daily balance requirement that, when maintained throughout the statement cycle, results in the monthly maintenance fee being waived completely. The specific dollar amounts differ by tier and should be confirmed directly with U.S. Bank at the time of account opening since these can be updated.
For freelancers with relatively stable income, this method works well. Keep a buffer in your checking account that sits above the waiver threshold at all times.
Method 2 (corrected): Business Essentials does not need a qualifying-transaction waiver, because it is $0 flat. The six qualifying transactions figure relates to the $400 new-account bonus promotion, not to the monthly fee. For Gold and Platinum, fee waivers depend on Payment Solutions use or the balance tiers listed in the fee table above.
Method 3: Maintain a combined balance across multiple U.S. Bank products.
Some account tiers allow the waiver to be triggered by maintaining a minimum combined balance across all eligible U.S. Bank business products, including checking, savings, money market accounts, and certain credit products. This means if your checking account balance occasionally dips below the solo threshold, your savings account balance can make up the difference in the combined calculation.
The Slow Month Strategy
Here is what I actually do during slow freelance months.
I maintain a permanent, non-negotiable “buffer” in my business checking account that I mentally designate as untouchable operating capital. This buffer sits above the minimum balance waiver threshold for my account tier at all times, even in months when client income is lower than usual.
The buffer came from setting aside a portion of earnings during strong months specifically for this purpose. It took a few months of discipline to build it, but once it was there, I stopped thinking about monthly maintenance fees entirely.
If a slow month means my incoming client payments are lower, I simply spend less on business expenses during that month. The buffer protects my waiver status while I wait for the next wave of client work.
One practical tip: Set up a low balance alert in your U.S. Bank mobile app that notifies you when your checking account balance drops below a custom threshold you set. I set mine at twice the minimum balance waiver amount so I get the notification while I still have plenty of time to transfer funds from savings if needed before the statement cycle closes.
U.S. Bank vs. the Competition: A Concise Comparison
In short: Chase offers a strong branch network and a well-regarded app, and its entry-level business checking is a direct alternative to Business Essentials. Bank of America offers strong digital and bookkeeping integrations and tends to appeal more to larger small businesses. Wells Fargo’s Initiate Business Checking is comparable to Business Essentials, though some freelancers weigh its past reputation issues. Online-only banks such as Bluevine, Mercury, Relay, and Novo often charge no monthly fee and suit fully digital freelancers, but cannot offer in-person cash deposits, notary services, or face-to-face dispute help. No single option wins on every criterion — choose based on whether you prioritize branch access, digital tools, or cost.
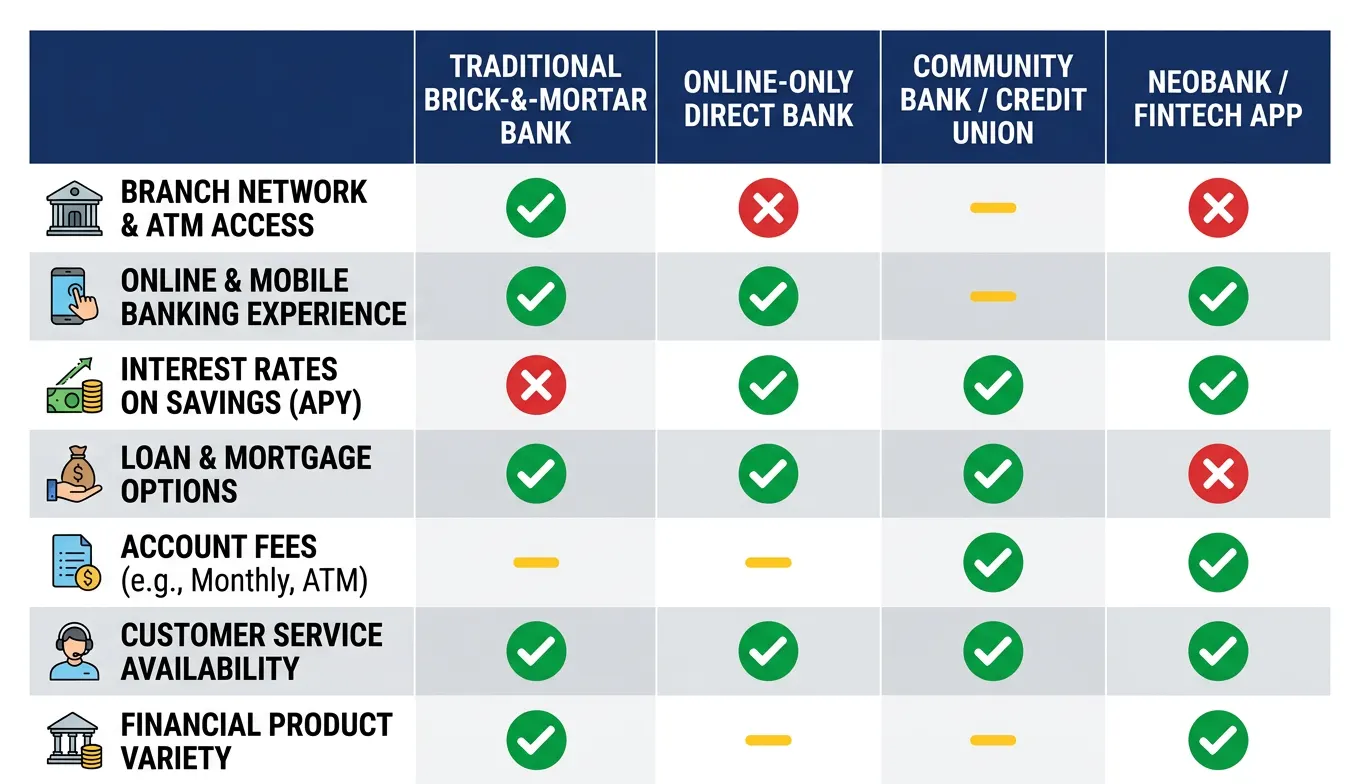
The decision is not about which type of bank is objectively better. It is about which type of bank fits your specific operational reality.
The Honest Limitations of US Bank Business Accounts in 2026
I promised at the beginning of this guide that I would pull no punches. So before I get to the FAQ section, I want to explicitly name the areas where U.S. Bank business accounts fall short compared to the competition.
Limitation 1: Interest rates on savings are not market-leading.
If maximizing the Annual Percentage Yield on your business reserve funds is your primary goal, U.S. Bank’s business savings rates are not going to be at the top of the comparison charts. Online-only banks and some credit unions consistently offer higher APY on savings balances. If you want to earn the absolute most interest on your tax buffer, you will need to look beyond U.S. Bank for that specific function.
Limitation 2: Customer service consistency is a legitimate concern.
Some U.S. Bank business customers have excellent, seamless experiences. Others have encountered frustrating delays in resolving account issues, difficulty reaching knowledgeable representatives, and slow processing of disputes. This inconsistency is a real risk, particularly for new account holders who experience a verification hold or an account access issue early in their banking relationship.
Limitation 3: Fee structure complexity.
U.S. Bank’s business account fee schedule is not the simplest in the industry to understand. Transaction limits, per-item fees, cash deposit thresholds, wire transfer charges, and monthly maintenance fee waiver conditions create a layered fee environment that requires careful reading. If you do not read the terms carefully before opening your account, you can find yourself paying fees you did not anticipate.
Limitation 4: Online account opening limitations for complex structures.
If your business has a more complex legal structure, meaning multiple LLC members, a corporate structure with multiple authorized signers, or non-standard ownership arrangements, the online application path may not work for you. You will need to visit a branch and the process may take longer than the streamlined online experience suggests.
Limitation 5: Geographic coverage gaps.
While U.S. Bank has a meaningful branch network, it is not as nationally uniform as Chase or Bank of America. In certain states, particularly in the Southeast and parts of the Northeast, U.S. Bank branch access is limited. If you live in an area with sparse U.S. Bank presence and you value in-person banking, this matters.
Naming these limitations is not a reason to avoid U.S. Bank. It is information you need to make an honest, well-informed decision about where to put your business money.
Building Your Complete Freelance Banking System Around US Bank Business Accounts in 2026
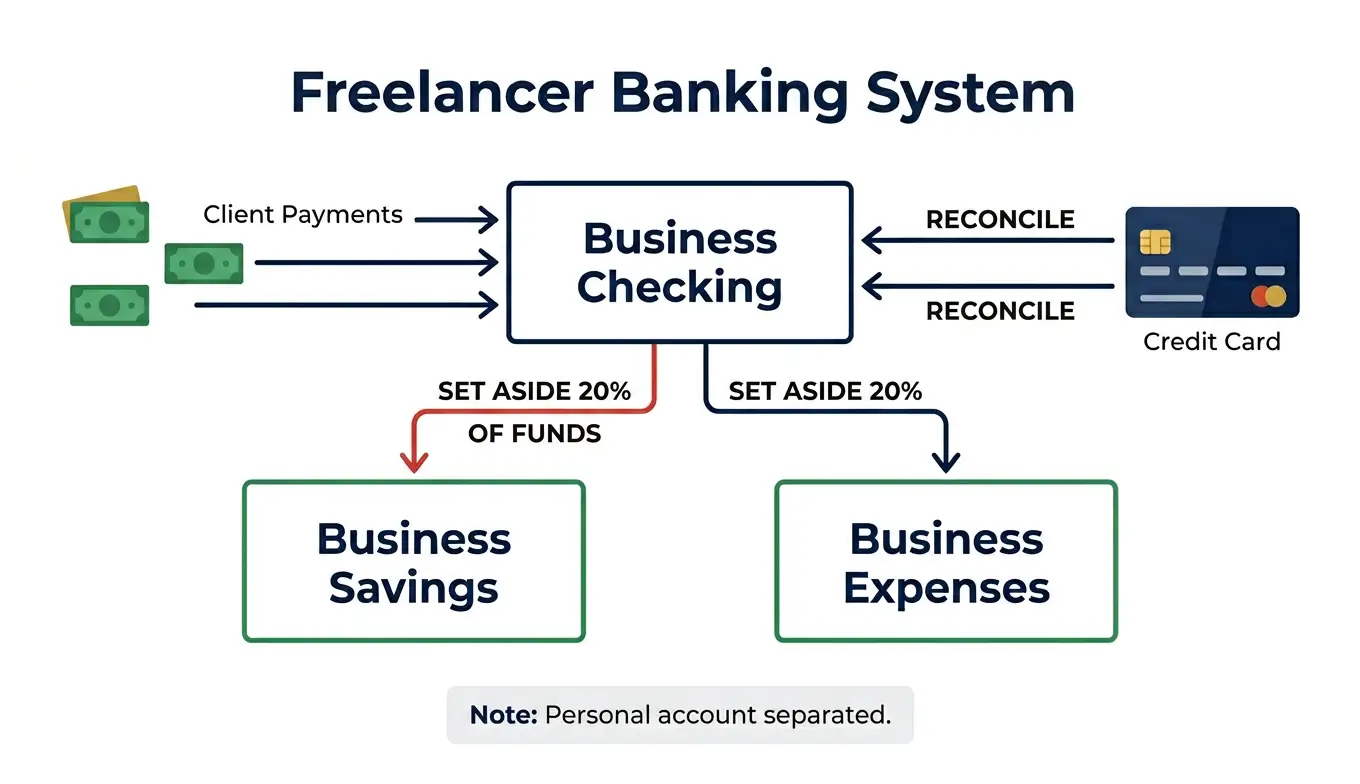
The most effective freelance financial system in 2026 uses us bank business accounts as the operational foundation, pairing a business checking account for daily cash flow with a business savings account for tax reserves and emergency capital.
I want to give you the specific system I use. Not a theoretical framework. The actual structure.
Account 1: US Bank Business Essentials Checking
This is my operational hub. Every single client payment comes into this account. Every business expense goes out of this account. Nothing else. No personal transactions. No personal bill payments. No grocery purchases. This account is for business activity only, and that discipline is non-negotiable.
Account 2: US Bank Business Savings
Every time a client payment arrives in my checking account, an automatic transfer moves 28 percent of that payment into my business savings account within 24 hours. I chose 28 percent because my tax liability as a self-employed individual in my income bracket, accounting for both federal self-employment tax and state income tax, consistently lands around 26 to 27 percent of net income. The extra 1 to 2 percent builds a small cushion against any calculation errors.
I treat this savings account as completely inaccessible for anything except tax payments and genuine operational emergencies. Period.
Account 3: A separate high-yield personal savings account (not U.S. Bank)
I keep my personal emergency fund at an online-only institution that currently offers a higher APY than U.S. Bank business savings. This is personal money. It has nothing to do with my business accounts. But I mention it because a complete financial system for a freelancer includes both business and personal layers, and optimizing each layer separately for its specific purpose makes financial sense.
The one credit card I use:
I have a U.S. Bank business credit card linked to my business banking dashboard. I use it for every recurring business software subscription and every business-related purchase where the credit card is accepted. I pay the full balance every single statement cycle. This gives me an additional layer of purchase protection, builds my business credit profile, and creates a second organized expense record that supplements my checking account history.
The accounting integration:
My business checking account connects directly to my accounting software through the bank’s data export feature. Every Monday morning I spend about 15 minutes reviewing the previous week’s transactions in the accounting software dashboard. The entire process of categorizing income and expenses for a week of business activity takes less time than making a pot of coffee.
That 15 minute weekly habit is what tax season looks like for me now. Not a multi-day scramble through a year of commingled transactions. Fifteen minutes per week.
This is what a well-organized banking system actually looks like in practice. And it starts with the simple decision to open a dedicated business account and keep it strictly separate from your personal finances.
Trending FAQs: Every Question Freelancers Ask About US Bank Business Accounts
What documents do I need to open a US Bank business account?
The specific documents depend on your business structure. Sole proprietors need a government-issued photo ID and their Social Security Number or EIN, plus a DBA certificate if operating under a business name. Single-member LLC owners need a photo ID, EIN, Articles of Organization, and an Operating Agreement if one exists. Corporations require additional documentation including Articles of Incorporation and a corporate resolution. Gathering these before you start the application makes the process smooth and fast.
How much does US Bank charge for a business account?
Monthly maintenance fees for U.S. Bank business accounts range from $0 for Business Essentials and Nonprofit Checking to $20 for Gold, $30 for Platinum, and $34 for Premium. Gold and Platinum fees can be waived as listed in the fee table; Essentials and Nonprofit are $0 flat and Premium is offset by an earnings credit. Beyond the monthly fee, per-item transaction fees apply once you exceed your free allowance, and wire transfers carry separate fees: domestic outgoing $30 digital, $40 branch, $45-$50 voice; incoming $14-$16; international outgoing $45 digital USD and $75 FX.
Can I open a US Bank business account online?
Yes. U.S. Bank allows online business account applications for many account types and business structures in 2026. The Business Essentials account is specifically designed to support digital onboarding. Most sole proprietors and single-member LLCs can complete the application entirely online with document uploads and digital identity verification. Some complex business structures still require an in-person branch visit. The online application typically takes under 30 minutes when documents are ready, and approval often comes within one to two business days.
What is the minimum balance for US Bank business checking?
The minimum balance requirements vary by account tier. Business Essentials and Nonprofit Checking are $0 flat and need no waiver. For Gold and Platinum, maintaining the balance or Payment Solutions conditions listed in the fee table waives the monthly maintenance fee. Always confirm the current specific dollar amounts directly with U.S. Bank at account opening, as these figures can be updated periodically.
Does US Bank offer free business checking in 2026?
The Business Essentials account is a no-fee checking account at $0 flat, with unlimited digital transactions and 25 free teller and paper transactions per statement cycle. Gold and Platinum carry monthly fees that can be waived through the balance or Payment Solutions conditions in the fee table; Silver is not presented as a current option because its current availability could not be confirmed.
How long does it take to open a US Bank business account?
Online applications for Business Essentials accounts are typically reviewed and approved within one to two business days. In-branch applications for standard account types can often be completed and approved the same day. After approval, your business debit card arrives by mail within five to seven business days. Online banking access is usually activated the same day your account is approved, so you can begin transacting digitally before your physical card arrives.
Is US Bank good for small businesses?
U.S. Bank is a strong choice for small businesses that value a combination of physical branch access, a well-developed digital banking platform, integrated payment acceptance, and a lending ecosystem they may grow into over time. It is a particularly good fit for freelancers and solo operators in markets where U.S. Bank has strong geographic presence. It is a less ideal fit for fully digital operators who prioritize maximum interest rates on savings and want zero-fee banking with absolutely no minimum balance considerations.
What are the benefits of a US Bank business account?
The core benefits include FDIC insured deposit protection up to $250,000, a well-rated mobile banking app with mobile deposit and Zelle integration, a business Visa debit card for organized expense tracking, integrated card payment acceptance with same-day funding through Business Essentials, access to business savings and money market accounts within the same banking relationship, fraud monitoring and BSA and AML compliant security protocols, multi-user access through the Shared Access feature, and a pathway into U.S. Bank’s broader business lending ecosystem including SBA loans and business lines of credit.
Can a sole proprietor open a US Bank business account?
Yes, absolutely. Sole proprietors are among the most common U.S. Bank business account customers. The account opening requirements for sole proprietors are minimal: a government-issued photo ID, your Social Security Number or EIN, and a DBA certificate if you operate under a business name different from your legal name. You do not need a formal LLC or corporation to open a business account. Operating as a sole proprietor is a recognized business structure that qualifies for all standard business account tiers.
What is the difference between a US Bank business account and a personal account?
Business accounts are legally structured for commercial activity, include features like multi-user access, merchant services integration, higher transaction volumes, and business-specific tools like payroll management access and cash flow monitoring. Personal accounts are designed for individual consumer use with consumer-level protections and features. Mixing business income with a personal account creates legal, tax, and record-keeping complications. Maintaining strictly separate accounts for business activity is widely recommended, regardless of business size or structure.
How do I waive the US Bank business account monthly fee?
The most straightforward method is maintaining an average daily balance above the required threshold for your specific account tier throughout the statement cycle. Business Essentials needs no waiver because it is $0 flat. For Gold, the waiver is Payment Solutions or $10,000, $20,000 combined, or $50,000 combined with credit balances. For Platinum, the waiver is Payment Solutions or $25,000, or $75,000 combined. Always ask your U.S. Bank representative to confirm the exact waiver conditions for your specific account at the time of opening, and set up a low balance alert in the mobile app to protect yourself during slow income months.
Does a US Bank business account earn interest?
Standard business checking accounts at U.S. Bank, including Business Essentials, Gold, and Platinum, do not earn interest in the traditional savings sense. They are transactional accounts designed for cash flow management. The business savings account may earn interest, but no rate is stated here; discuss savings and money market options with a U.S. Bank business banker and check current terms.
What is the best US Bank business account for an LLC in 2026?
For most single-member LLC freelancers and solo operators in 2026, the Business Essentials account is the best starting point. It is $0 flat, includes integrated card payment acceptance, provides full access to online banking and the mobile app, and comes with a business Visa debit card. As your LLC grows and your monthly transaction volume increases, stepping up to the Gold or Platinum tier becomes appropriate. Multi-member LLCs with higher operational complexity may want to start directly at the Gold or Platinum tier, depending on their expected transaction volume.
How many transactions are allowed per month on a US Bank business account?
The free transaction allowance varies by account tier. Business Essentials offers unlimited digital transactions with 25 free teller and paper transactions per statement cycle. Gold includes 350 free transactions, then $0.45 each. Platinum includes 550 free transactions, then $0.40 each. Nonprofit Checking includes 1,800 free transactions per calendar year, then $0.50 each. For most freelancers with a modest number of monthly client payments and business expense payments, the Business Essentials allowance is more than sufficient.
Can I open a US Bank business account without being physically present?
For most standard business structures, the online application process for U.S. Bank business accounts allows you to complete the application without visiting a branch. For foreign nationals or nonresidents attempting to open an account without an in-person presence, there is no published guarantee; confirm with a banker whether remote opening is possible for your situation.
What is the US Bank Business Essentials account and is it right for me?
The U.S. Bank Business Essentials account launched in April 2025 as an all-in-one solution combining business checking with integrated card payment acceptance and same-day funding. It is designed specifically for small businesses, solo operators, and freelancers who want a single account that handles both receiving client payments and managing operating expenses without requiring multiple separate merchant service arrangements. If you are a freelancer who invoices clients and occasionally accepts card payments, Business Essentials simplifies your payment ecosystem considerably and represents the best entry-level U.S. Bank business account option available in 2026.
How do I set up automatic tax savings with my US Bank business account?
The U.S. Bank online banking portal allows you to set up recurring automatic transfers between your business checking account and your business savings account. Log into your online banking dashboard, navigate to the transfers section, and set up a recurring transfer for a fixed percentage of your typical deposit amount to move from checking to savings on a regular schedule. Many self-employed individuals and freelancers set this up as a weekly transfer of a set dollar amount that approximates 25 to 30 percent of their average weekly earnings. Once configured, the system executes the transfer automatically without any manual action required, which removes the psychological friction of manually saving for taxes.
Is US Bank FDIC insured for business accounts?
Yes. U.S. Bank, operating as U.S. Bank National Association under the parent company U.S. Bancorp, is a member of the Federal Deposit Insurance Corporation. Business deposit accounts at U.S. Bank are insured up to $250,000 per depositor per ownership category. This means your business checking and savings account balances are federally protected up to that limit in the event of bank failure. For the vast majority of freelancers and small business owners, the $250,000 coverage limit is well above their typical business account balance, making the FDIC protection comprehensive and fully effective.
Does US Bank business account support Zelle?
Yes. U.S. Bank business accounts support Zelle in 2026. Zelle has become a widely used payment method for small business transactions, particularly for service-based businesses and freelancers who work with clients who prefer to pay through their own bank’s Zelle integration rather than through credit card or ACH transfer. The Zelle for business functionality is accessible through the U.S. Bank mobile app and online banking portal. Payments received through Zelle are typically available in your account within minutes, which makes it one of the fastest settlement options for client payments currently available.
What happens if my US Bank business account balance drops below the minimum?
If your average daily balance falls below the minimum threshold required to waive the monthly maintenance fee during a statement cycle, U.S. Bank will charge the monthly maintenance fee for that cycle. You will not lose access to your account or face additional penalties simply for dropping below the balance threshold. The fee is a maintenance charge, not a punitive overdraft fee. To avoid this, set up low balance alerts in the mobile app so you are notified well before the statement cycle closes if your balance is approaching the threshold, giving you time to transfer funds from savings if necessary.
Your Next Step: Making the Decision Today
Everything you need to know to make a confident, informed decision about us bank business accounts is now in front of you.
You know the account tiers and which one fits your freelance operation. You know the exact documents you need to gather. You know the strategies to waive monthly fees permanently. You know the honest limitations alongside the genuine strengths. You know how U.S. Bank stacks up against Chase, Bank of America, Wells Fargo, and online-only alternatives. And you know exactly how to build a two-account system that makes tax season feel like a routine administrative task rather than an annual financial crisis.
The only thing left is the decision itself.
If you are still depositing client payments into your personal checking account alongside your grocery charges and your streaming subscriptions, today is the day to fix that. Not next week. Not after your next big client payment lands. Today.
Open the U.S. Bank website. Start the Business Essentials application. Gather your documents. And build the financial foundation your freelance work actually deserves.
For additional guidance on protecting your business finances online and understanding your rights as a small business owner, the Federal Trade Commission’s business resources at ftc.gov/business-guidance provide reliable, government-backed information that every independent worker should be familiar with.
Your freelance business is real. Your money deserves a real home.
Disclaimer: Fee structures, interest rates, account features, and promotional offers mentioned in this article reflect publicly available information as of mid-2026. Banking products and their terms are subject to change. Always verify current terms directly with U.S. Bank before opening an account. This article is for informational purposes only and does not constitute financial advice.


4 Comments on “U.S. Bank Business Checking for Freelancers: Current Accounts and Costs”